FOR IMMEDIATE RELEASE
Premiums for Commercial P&C Moderate; Signs Market May Be Stabilizing
WASHINGTON, D.C. – Nineteen months after the World Trade Center attacks sent the market into turmoil, premium increases for commercial property/casualty insurance are moderating, and there are signs the marketplace is beginning to stabilize, according to the First Quarter 2003 Market Index survey by The Council of Insurance Agents & Brokers.
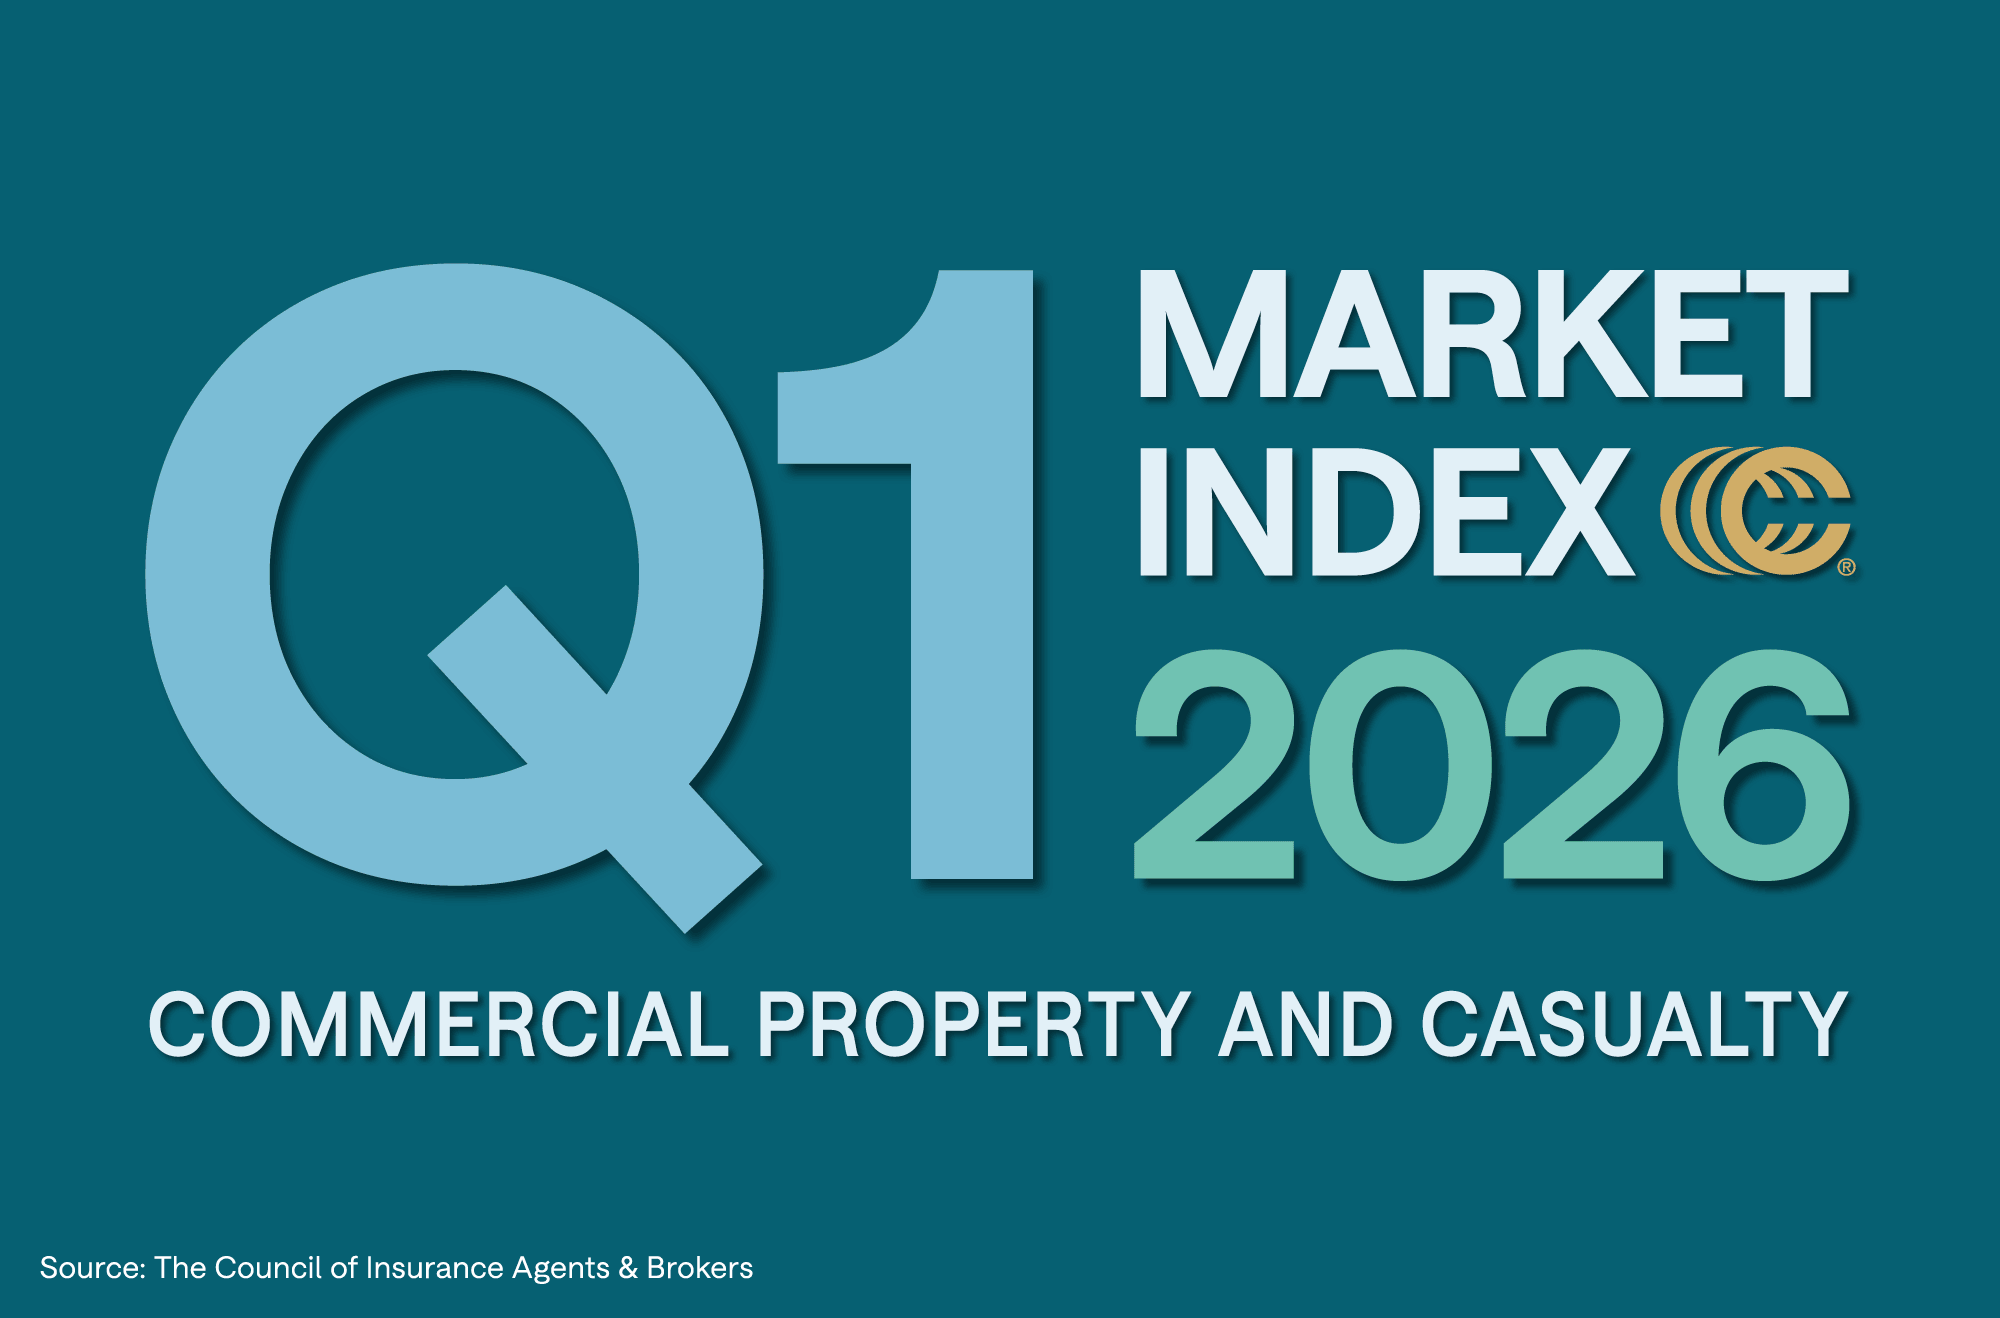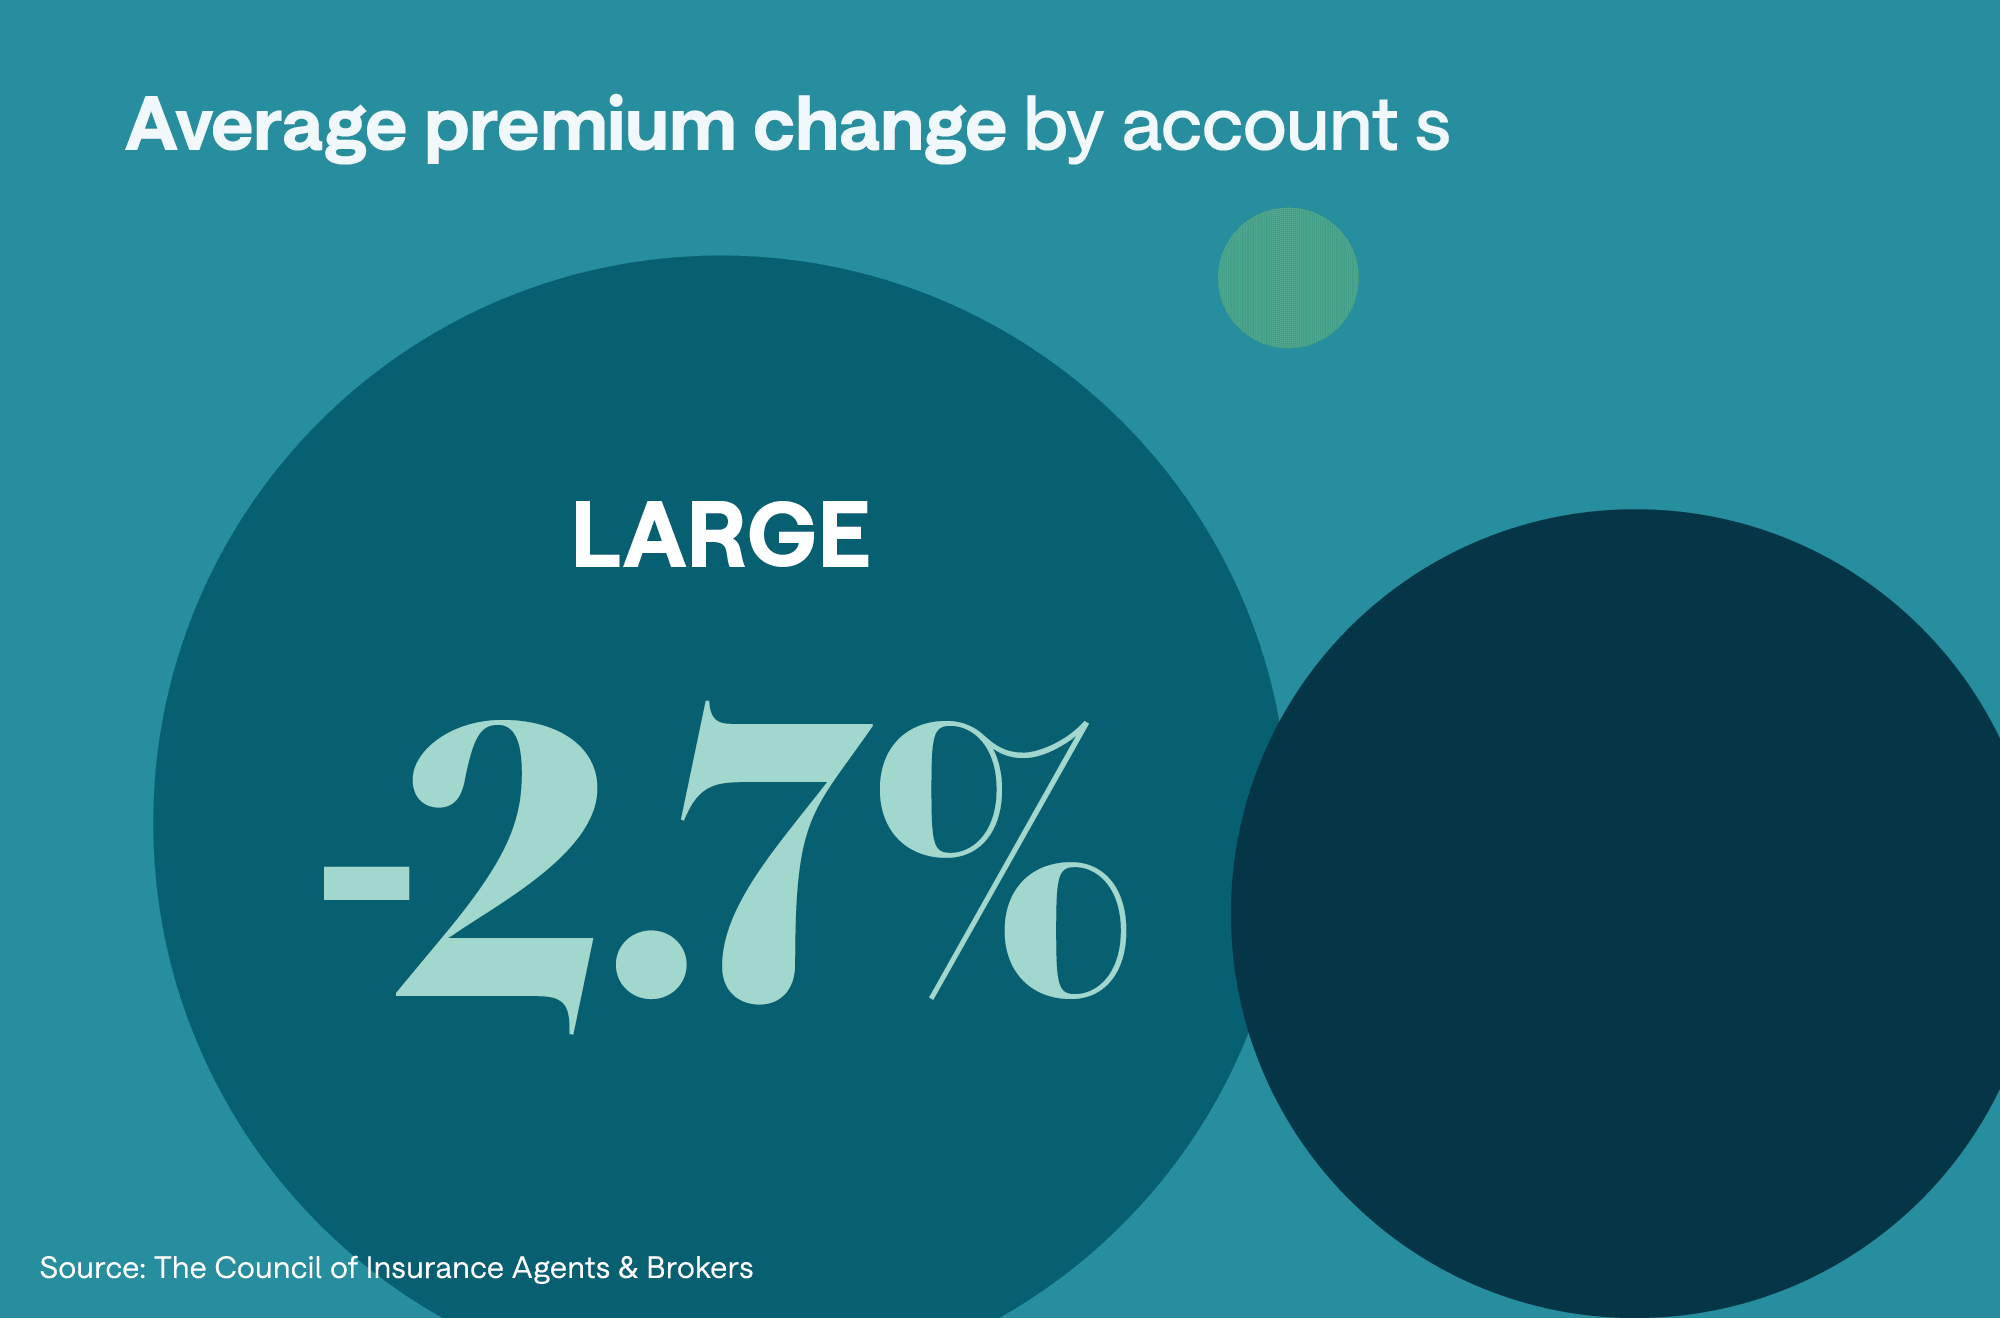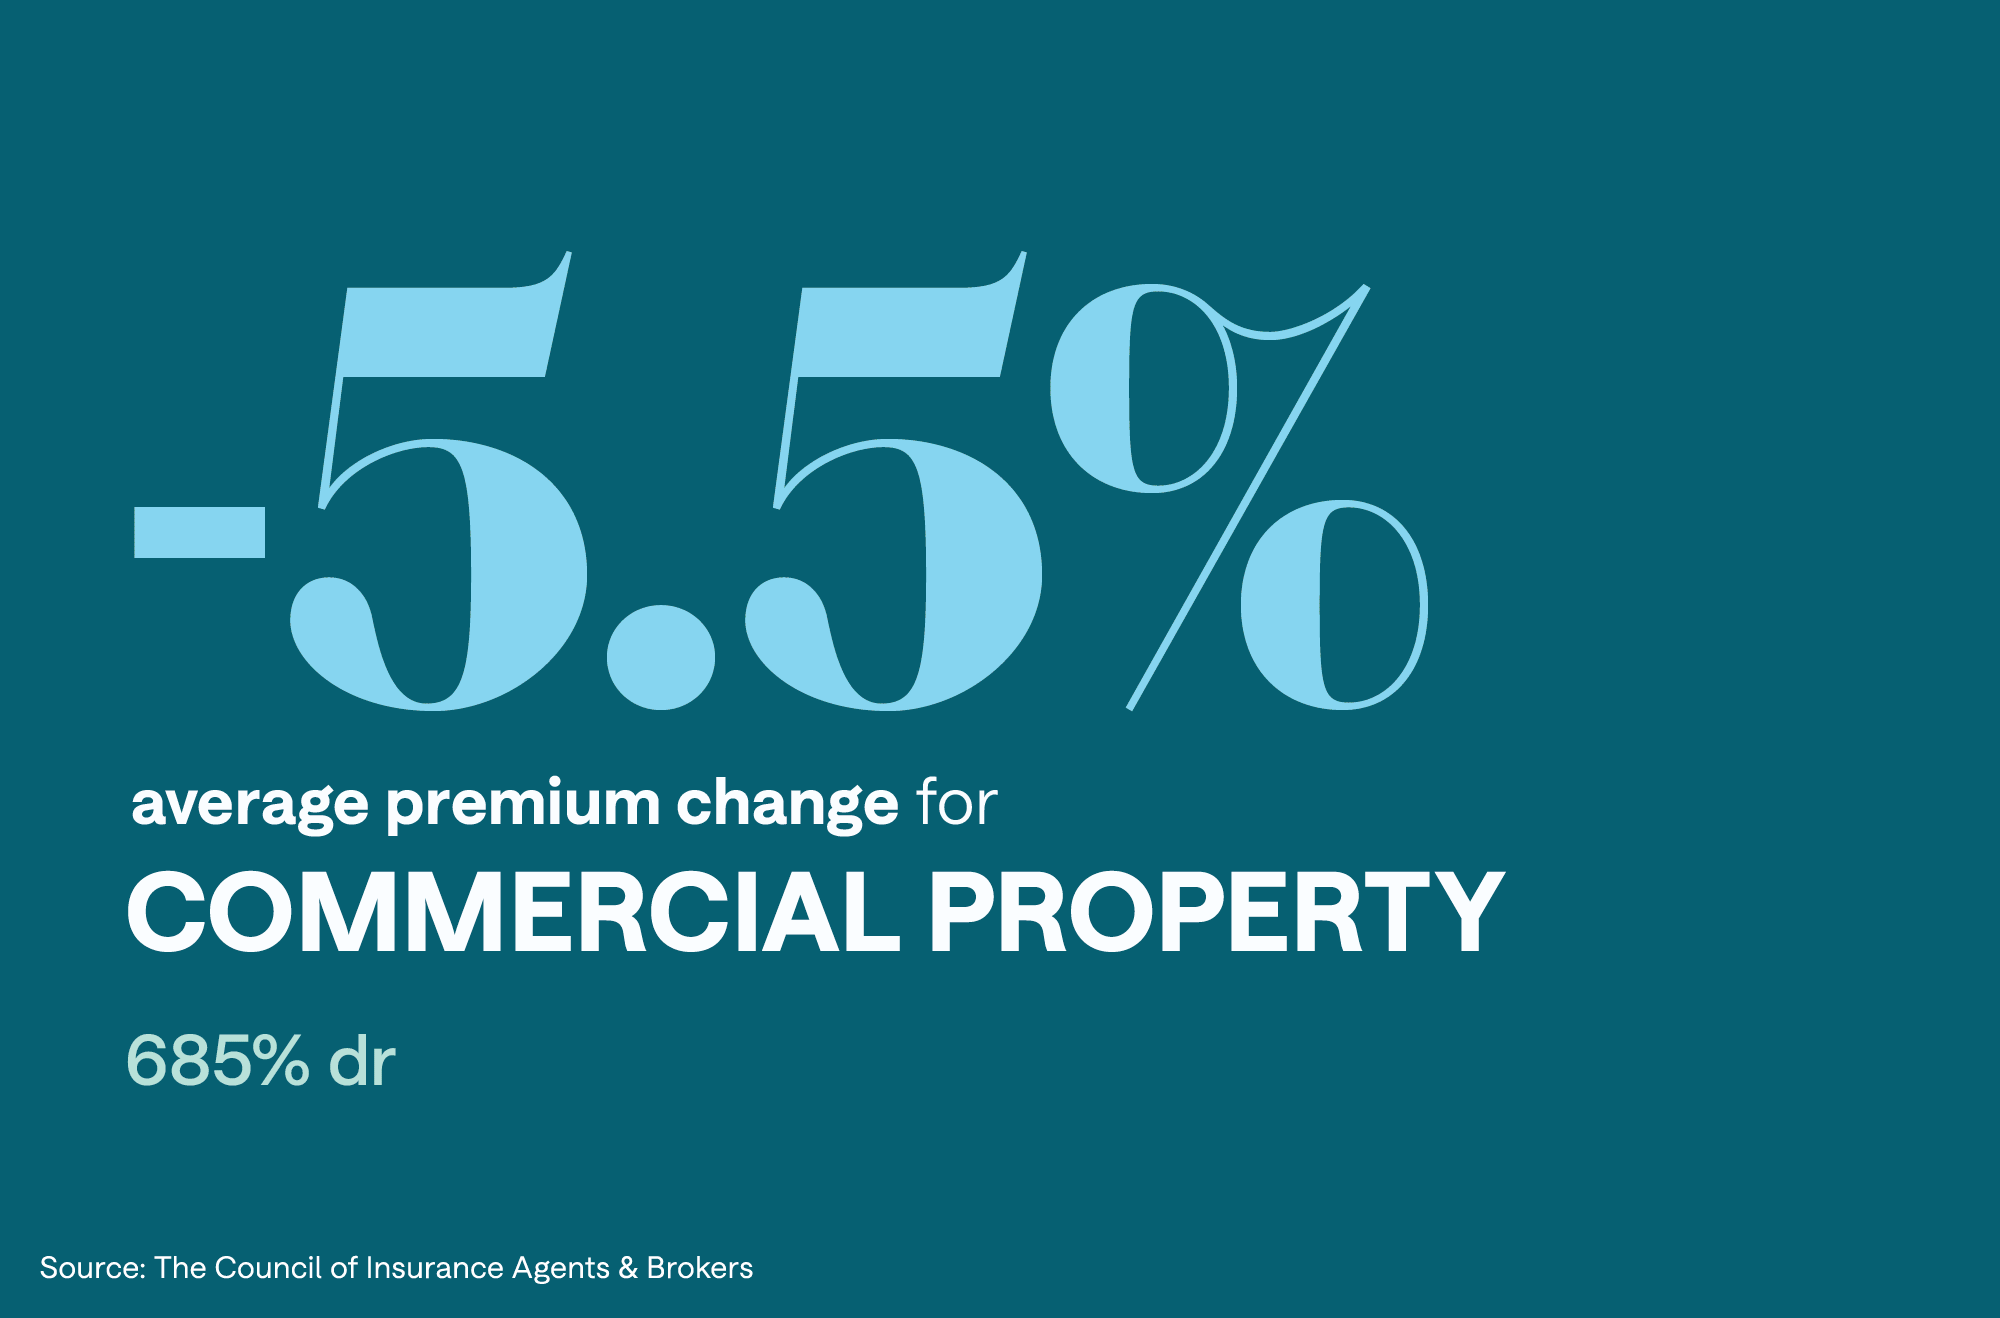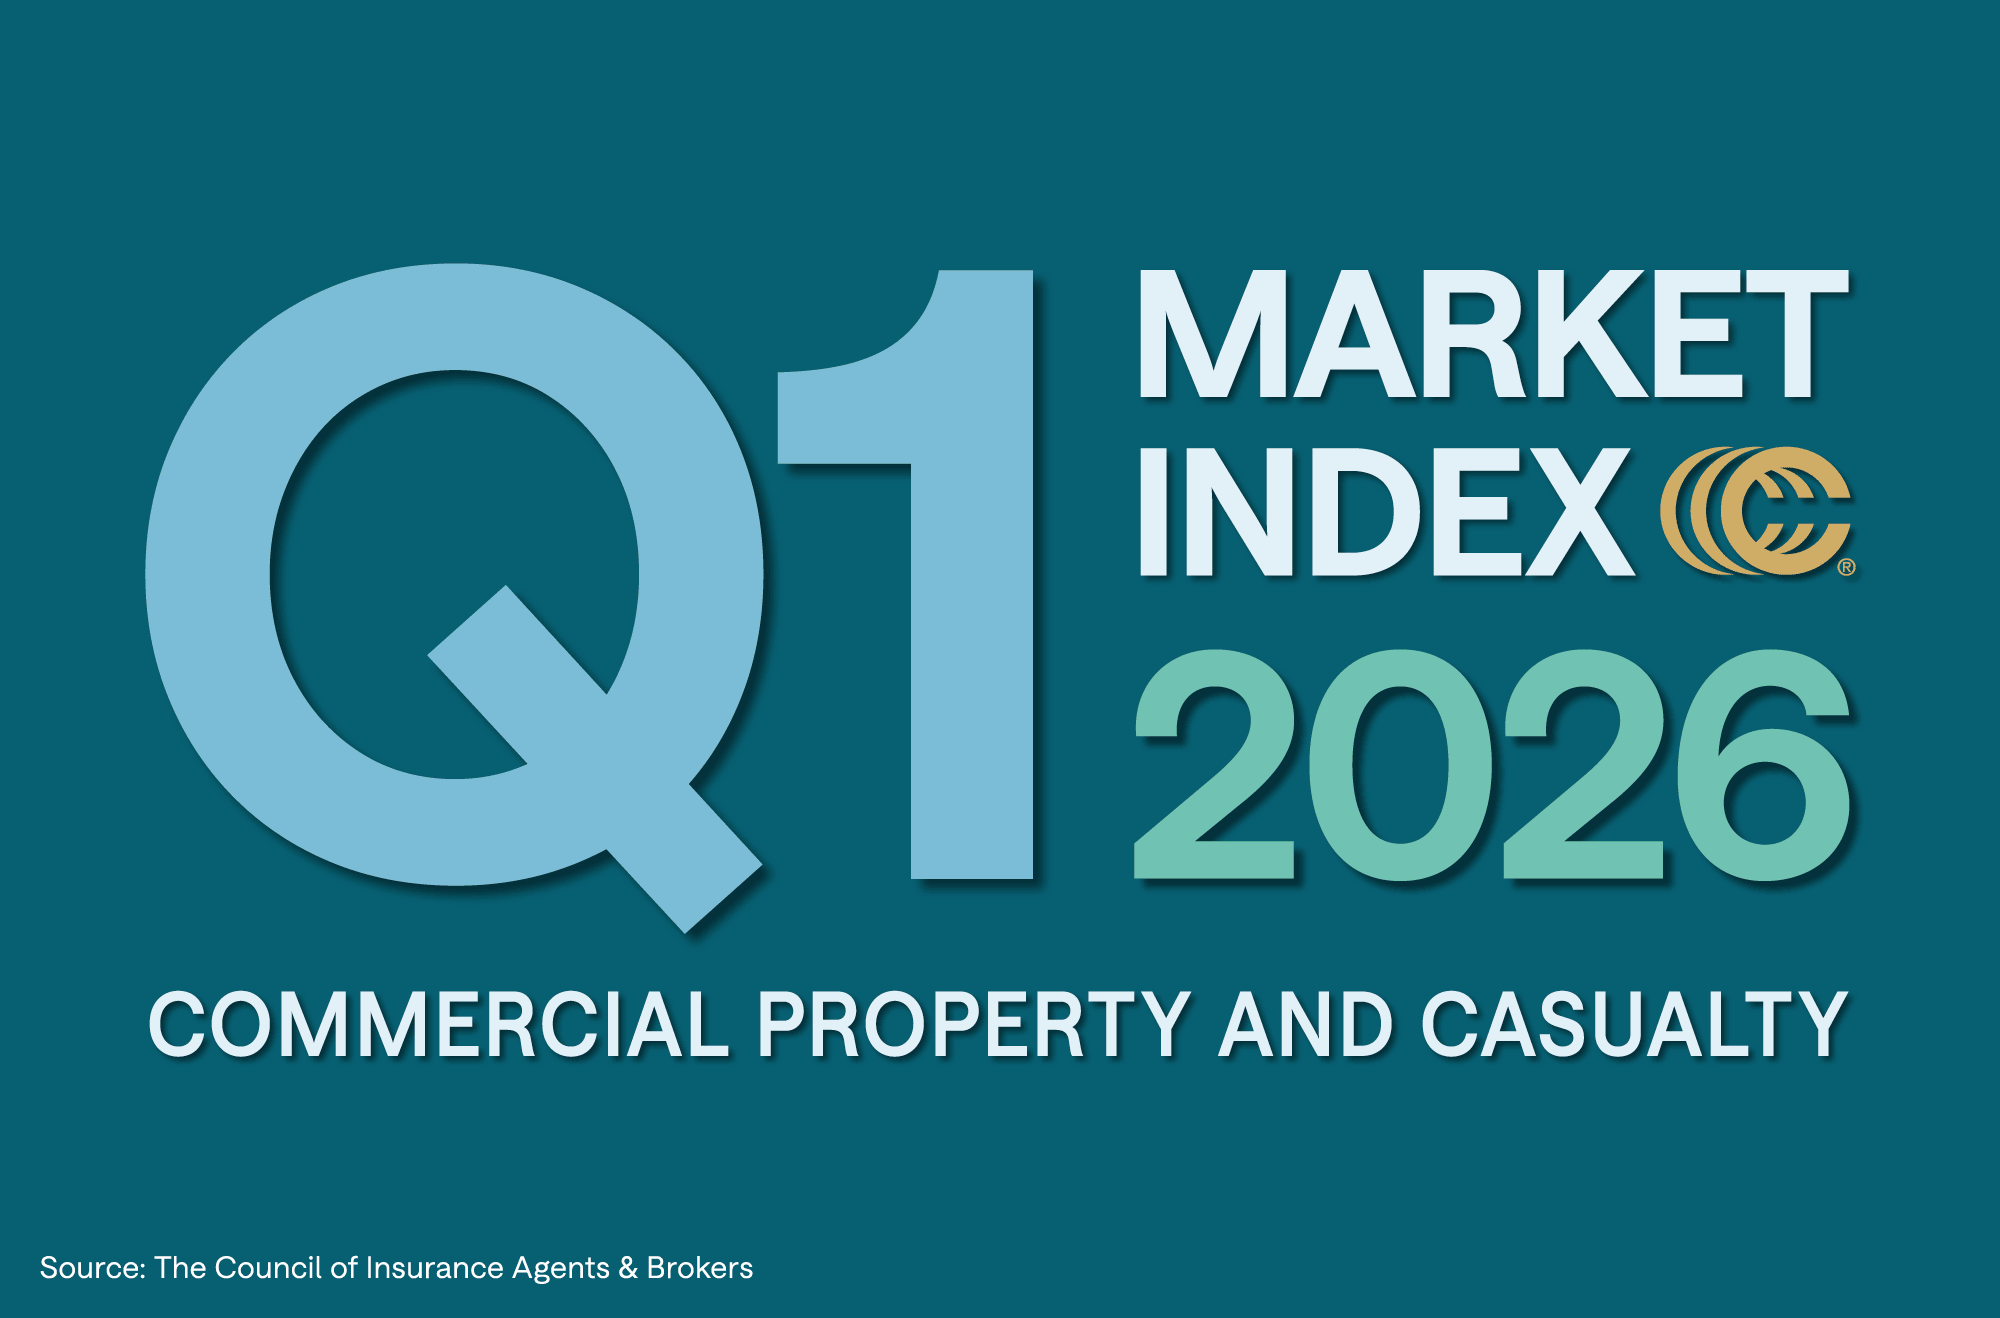
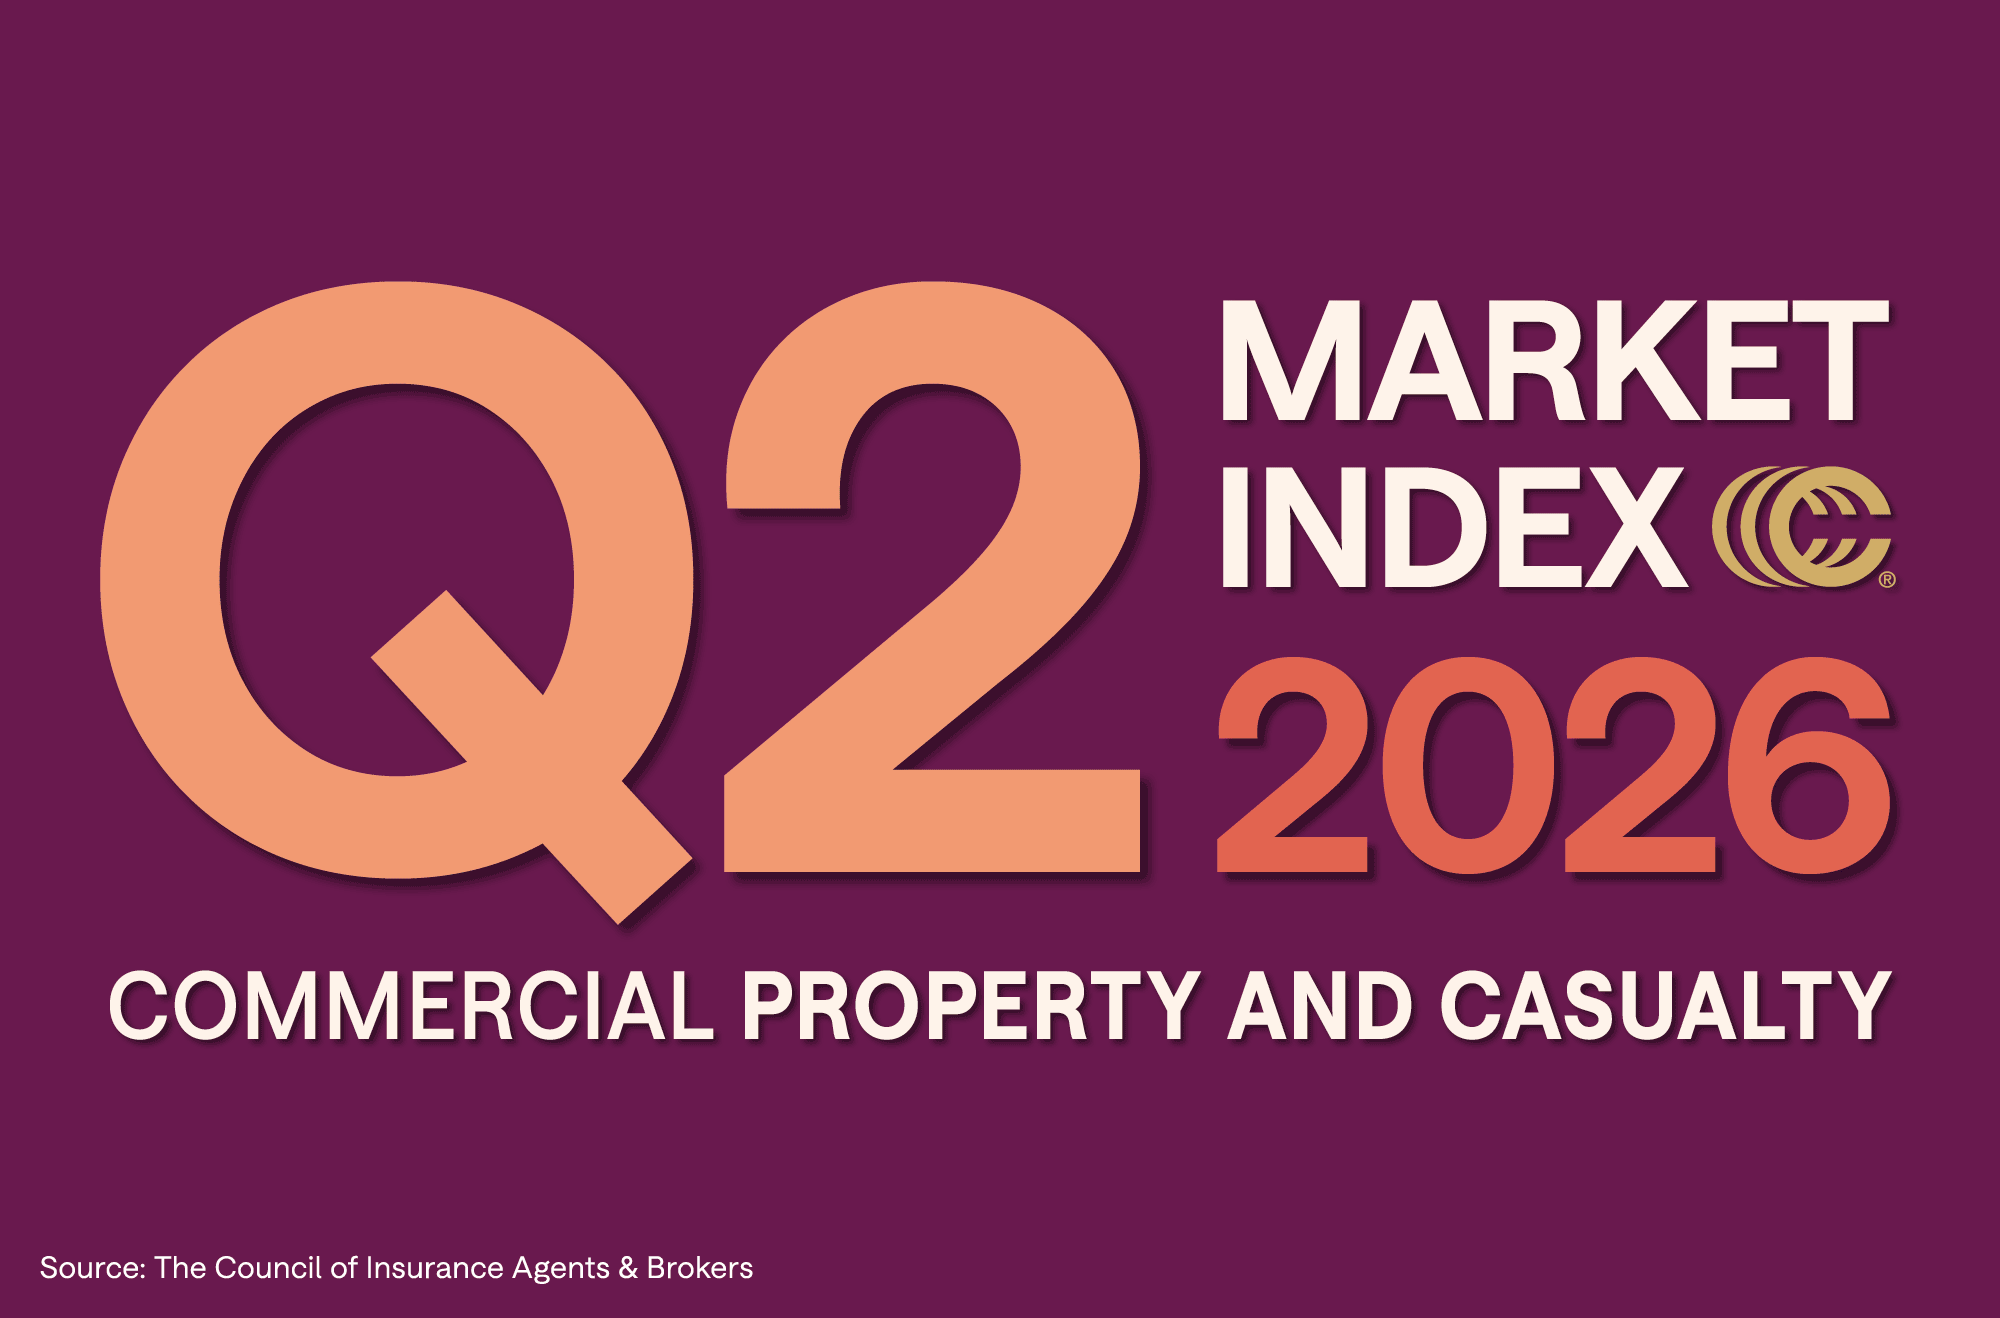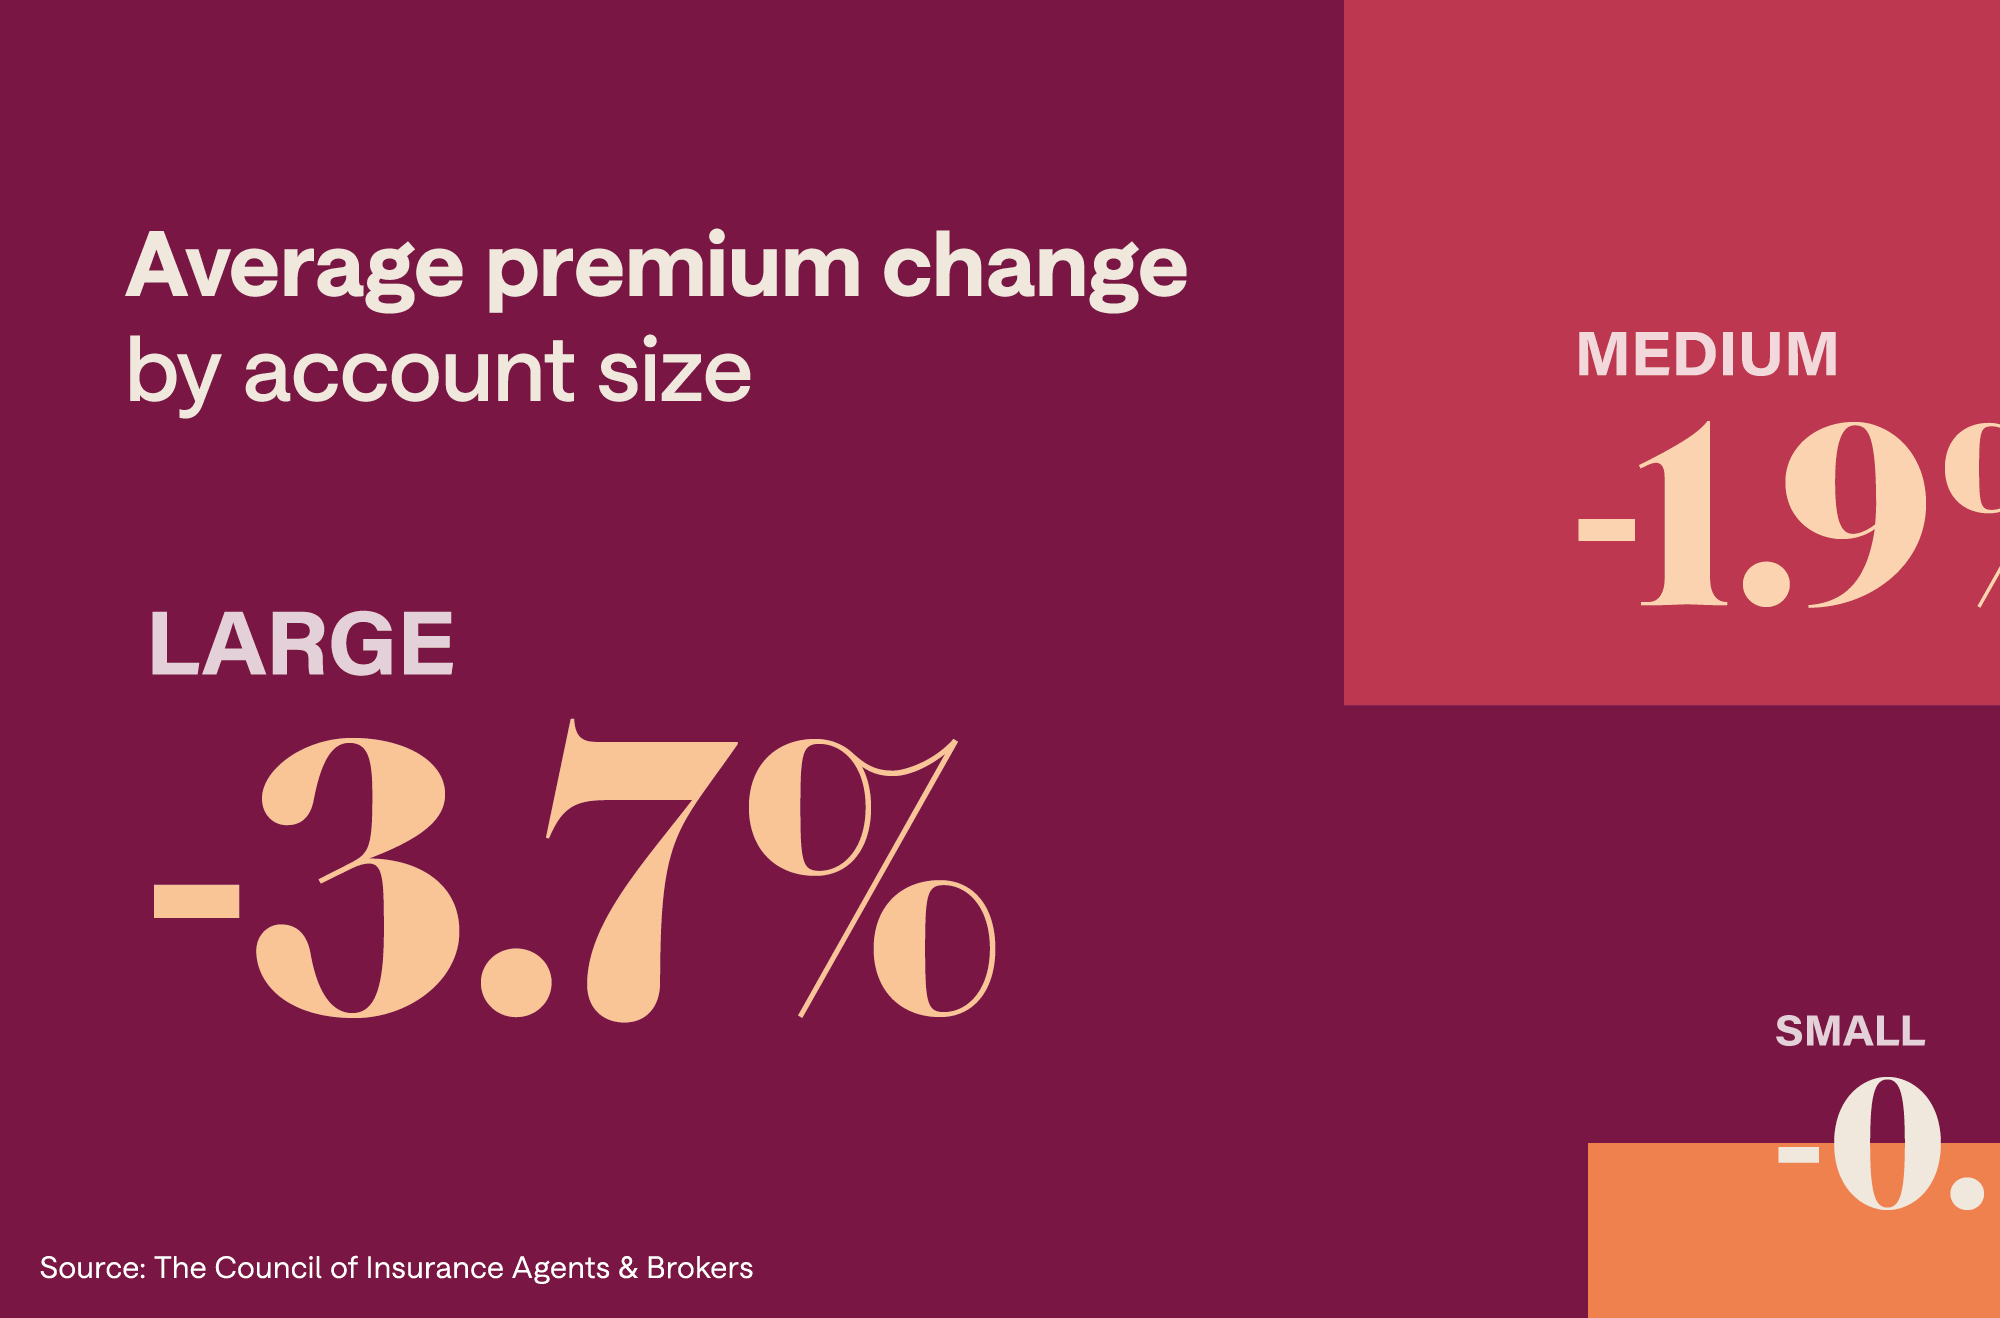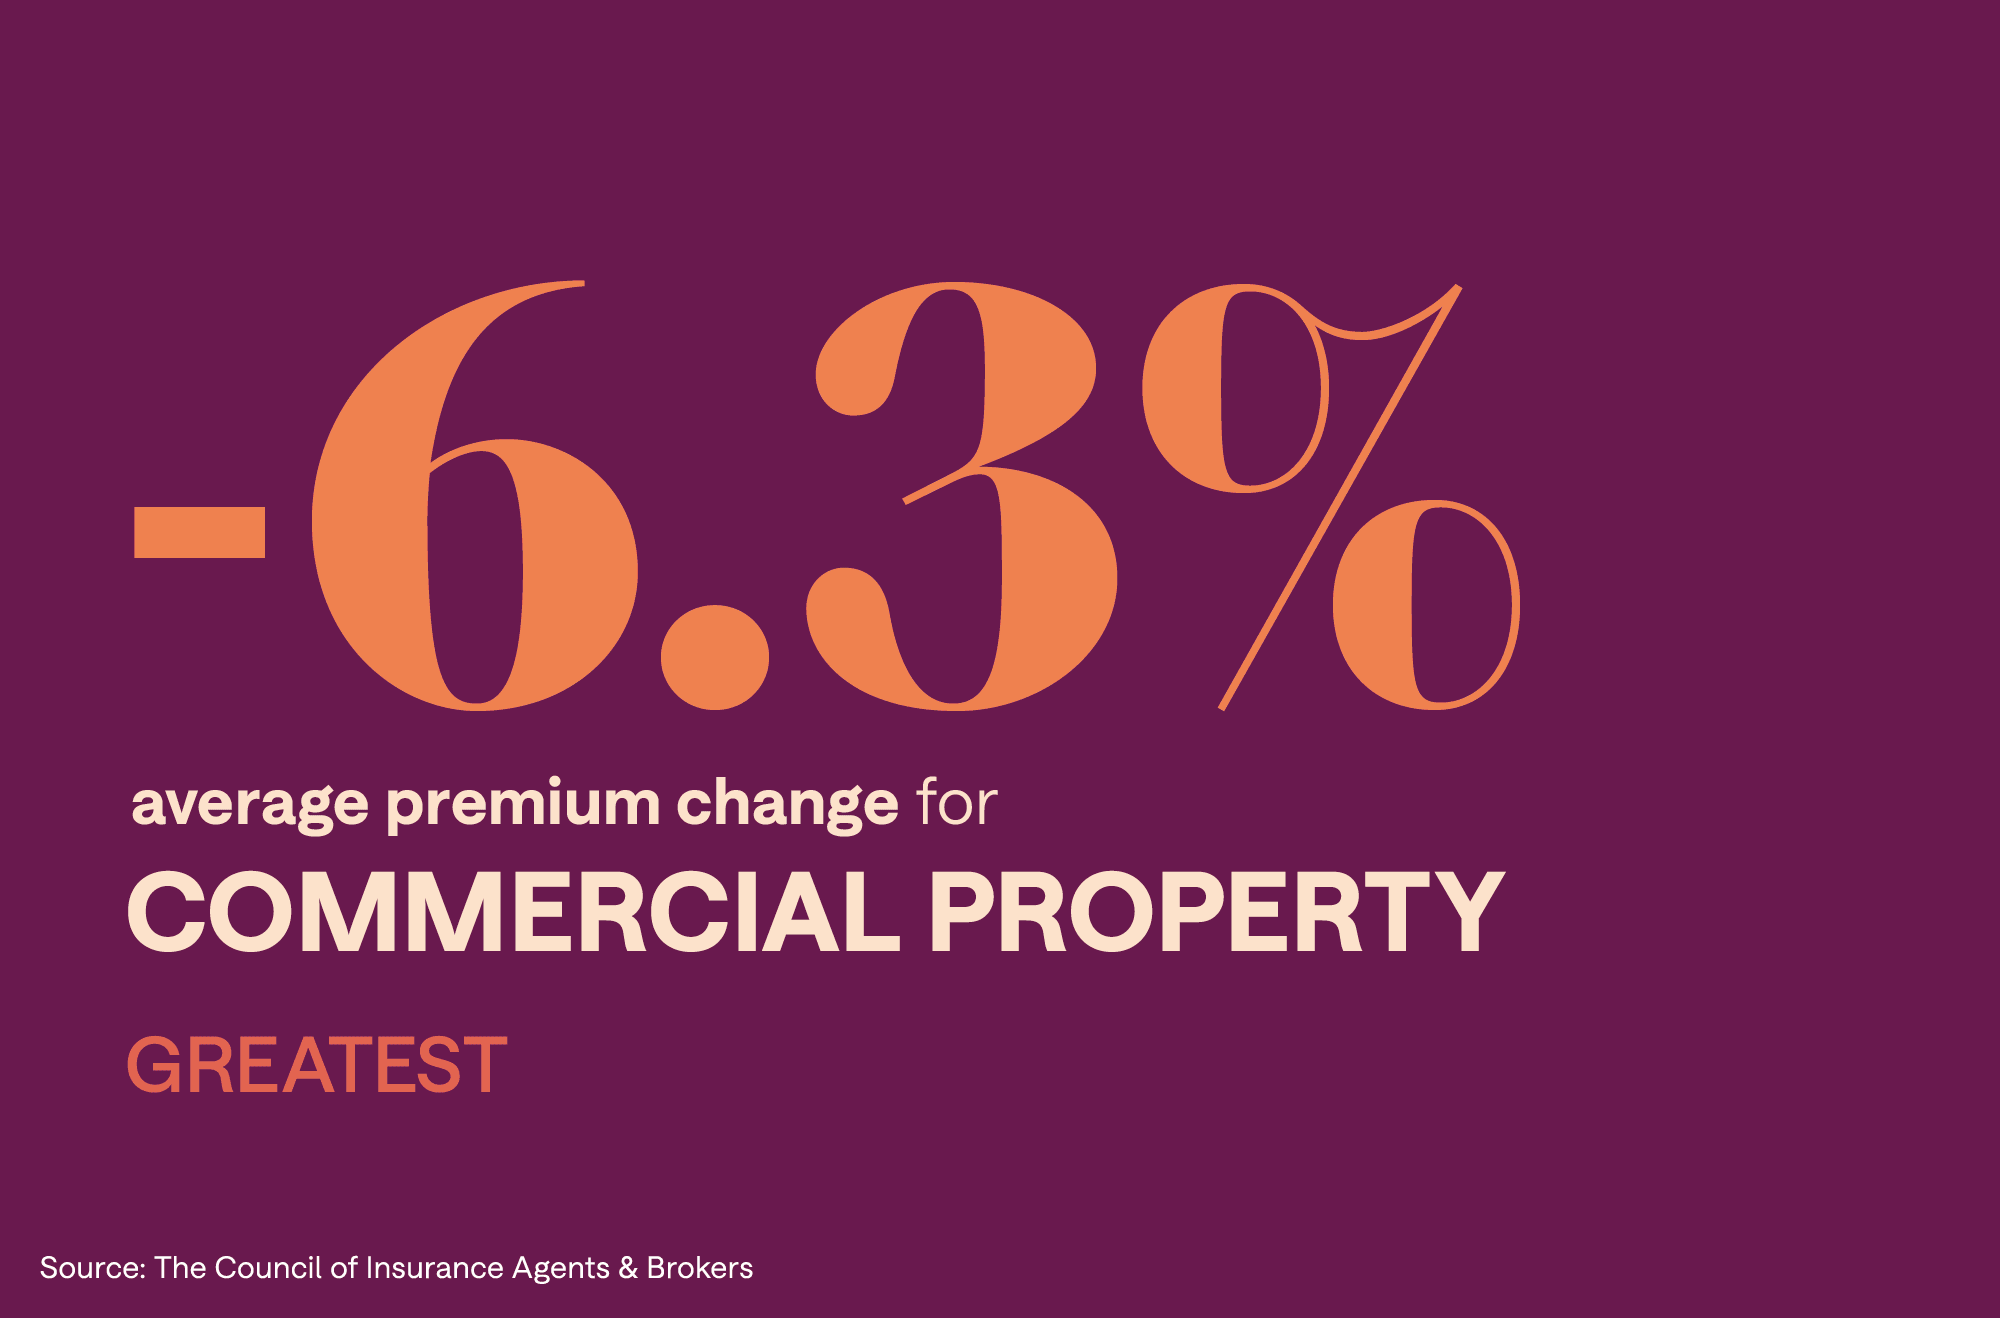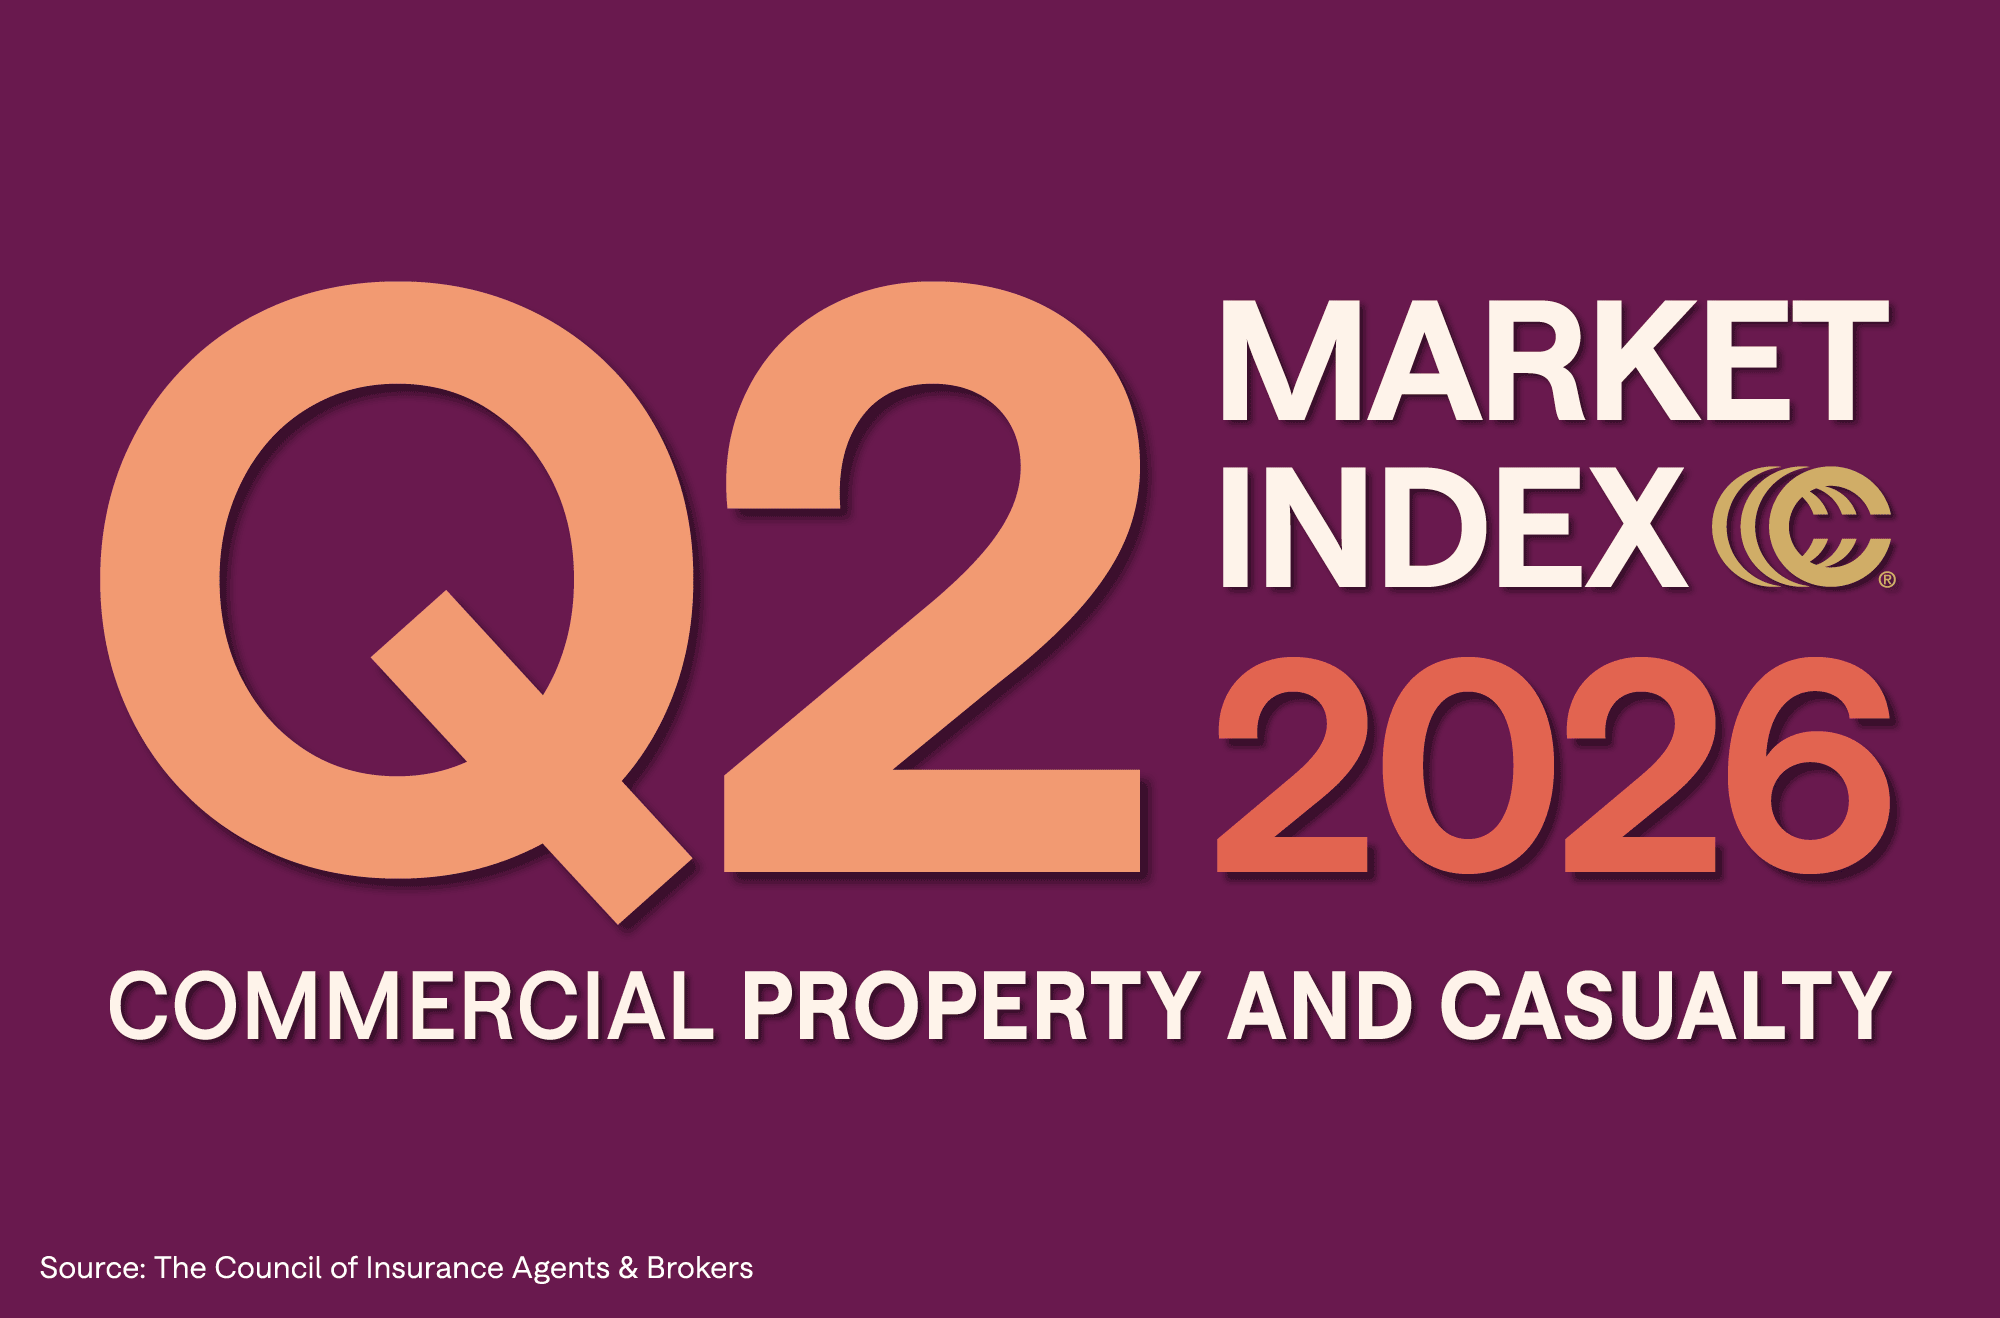
About two-thirds of small, medium and large accounts are still experiencing average increases of up to 20 percent for all lines of insurance. But unlike previous surveys, survey respondents said only a small proportion of their accounts had rate hikes in the 20 to 30 percent range. Only a small percentage of accounts saw rates go up more than that, while 12 percent of the small accounts and 8 percent of both medium and large accounts experienced no change at all in their commercial property/casualty premiums for renewals during the survey period.
Breaking insurance down by line, business interruption and commercial property showed the greatest moderation, with 16 percent of respondents reporting that premiums for those lines either were holding steady or dropping slightly. Conversely, medical malpractice premiums increased the most, with about one-third of the accounts experiencing rate hikes of from 30-100 percent, and an additional 8 percent rising by more than 100 percent.
The only other commercial lines to experience premium increases in the 30-50 percent range were umbrella policies, construction risks and D&O policies.
The Council represents the top tier of insurance brokers in the country who write 80 percent of the commercial property/casualty insurance premiums and administer billions of dollars in benefit accounts annually.
In responses to open-ended questions in the survey, the brokers said they did not consider the commercial market to be “softening” but instead used terms such as “stabilizing,” “flattening,” “relaxing,” “loosening” and “steadying” to describe market conditions.
“Not softening when rates are still climbing 20 percent,” said one broker in the Northeast, “but it appears underwriters are slightly more interested in quoting commercial business compared to six months ago.”
“Property rates are flat, a good indication that in another 12 to 15 months we’ll see softening,” added a broker from the Southwest.
As the hard market begins to turn the corner, capacity is still tight in a number of areas, and insurers continue to watch the risks they take on very carefully. While carriers may be more willing to compete on price, underwriters are still prevailing in terms of exclusions and the terms and conditions applied to risks.
Ken A. Crerar, president of The Council, said the survey suggests that in commercial property and business interruption, which have experienced the greatest price increases, the market is beginning to stabilize. This is particularly true in the Northeast, where rates had increased at the fastest clip.
“There are still exceptions in major metropolitan areas, especially when a trophy property or major tourist attraction is involved, but our members are reporting that more competitive pricing may be returning to the market,” Crerar said. “Carriers are also more willing to write risks than a year ago, another sign of market stabilization.”
“Things have settled down,” said a broker in the Northeast. “Seems like the standard markets have cleaned up their books and like what’s left.”
Construction coverage for both commercial and residential properties is still difficult to obtain, especially in the Pacific Northwest, because of concerns over class action suits relating to toxic mold and other environmental concerns, while professional liability coverage is hard to find and highly priced in all areas of the country, the survey showed.
Only 16 percent of the brokers surveyed said they had noticed an increase in the purchase of terrorism coverage since the war with Iraq began, and the respondents indicated that in many cases, only those required to by lenders are actually buying terrorism insurance.
“Main Street USA risks still don’t see the benefit of the additional cost,” said a broker from the Northeast.
“Classic case of adverse selection,” said another. “Those who do not feel exposed are choosing not to purchase coverage — a potential unfunded catastrophe should a certified terrorism event occur outside of major cities.”
Looking ahead to major market trends for the coming year, the brokers said they are watching the economic conditions carefully because of worries about potential insolvencies of both insurers and reinsurers. And the brokers said if there is another disaster, natural or manmade, any moderating trends would be short-lived.
P&C Market Survey Contact:
Zach West
Senior Content Specialist/Copy Chief, Leader’s Edge