FOR IMMEDIATE RELEASE
Commercial Property & Casualty Premium Rates Continue to Soften in First Quarter 2005
WASHINGTON, D.C. – Commercial property and casualty premiums continued to soften during the first quarter of 2005, with the average rates for all sizes of accounts reaching their lowest levels since the commercial insurance market peaked in the fourth quarter of 2001.
Survey data released today by The Council of Insurance Agents & Brokers showed almost 80 percent of large accounts were down more than 10 percent during the first quarter of 2005. Premiums for eight of 10 commercial lines in the survey for all account sizes were either stable or down as much as 20 percent, according to the survey.
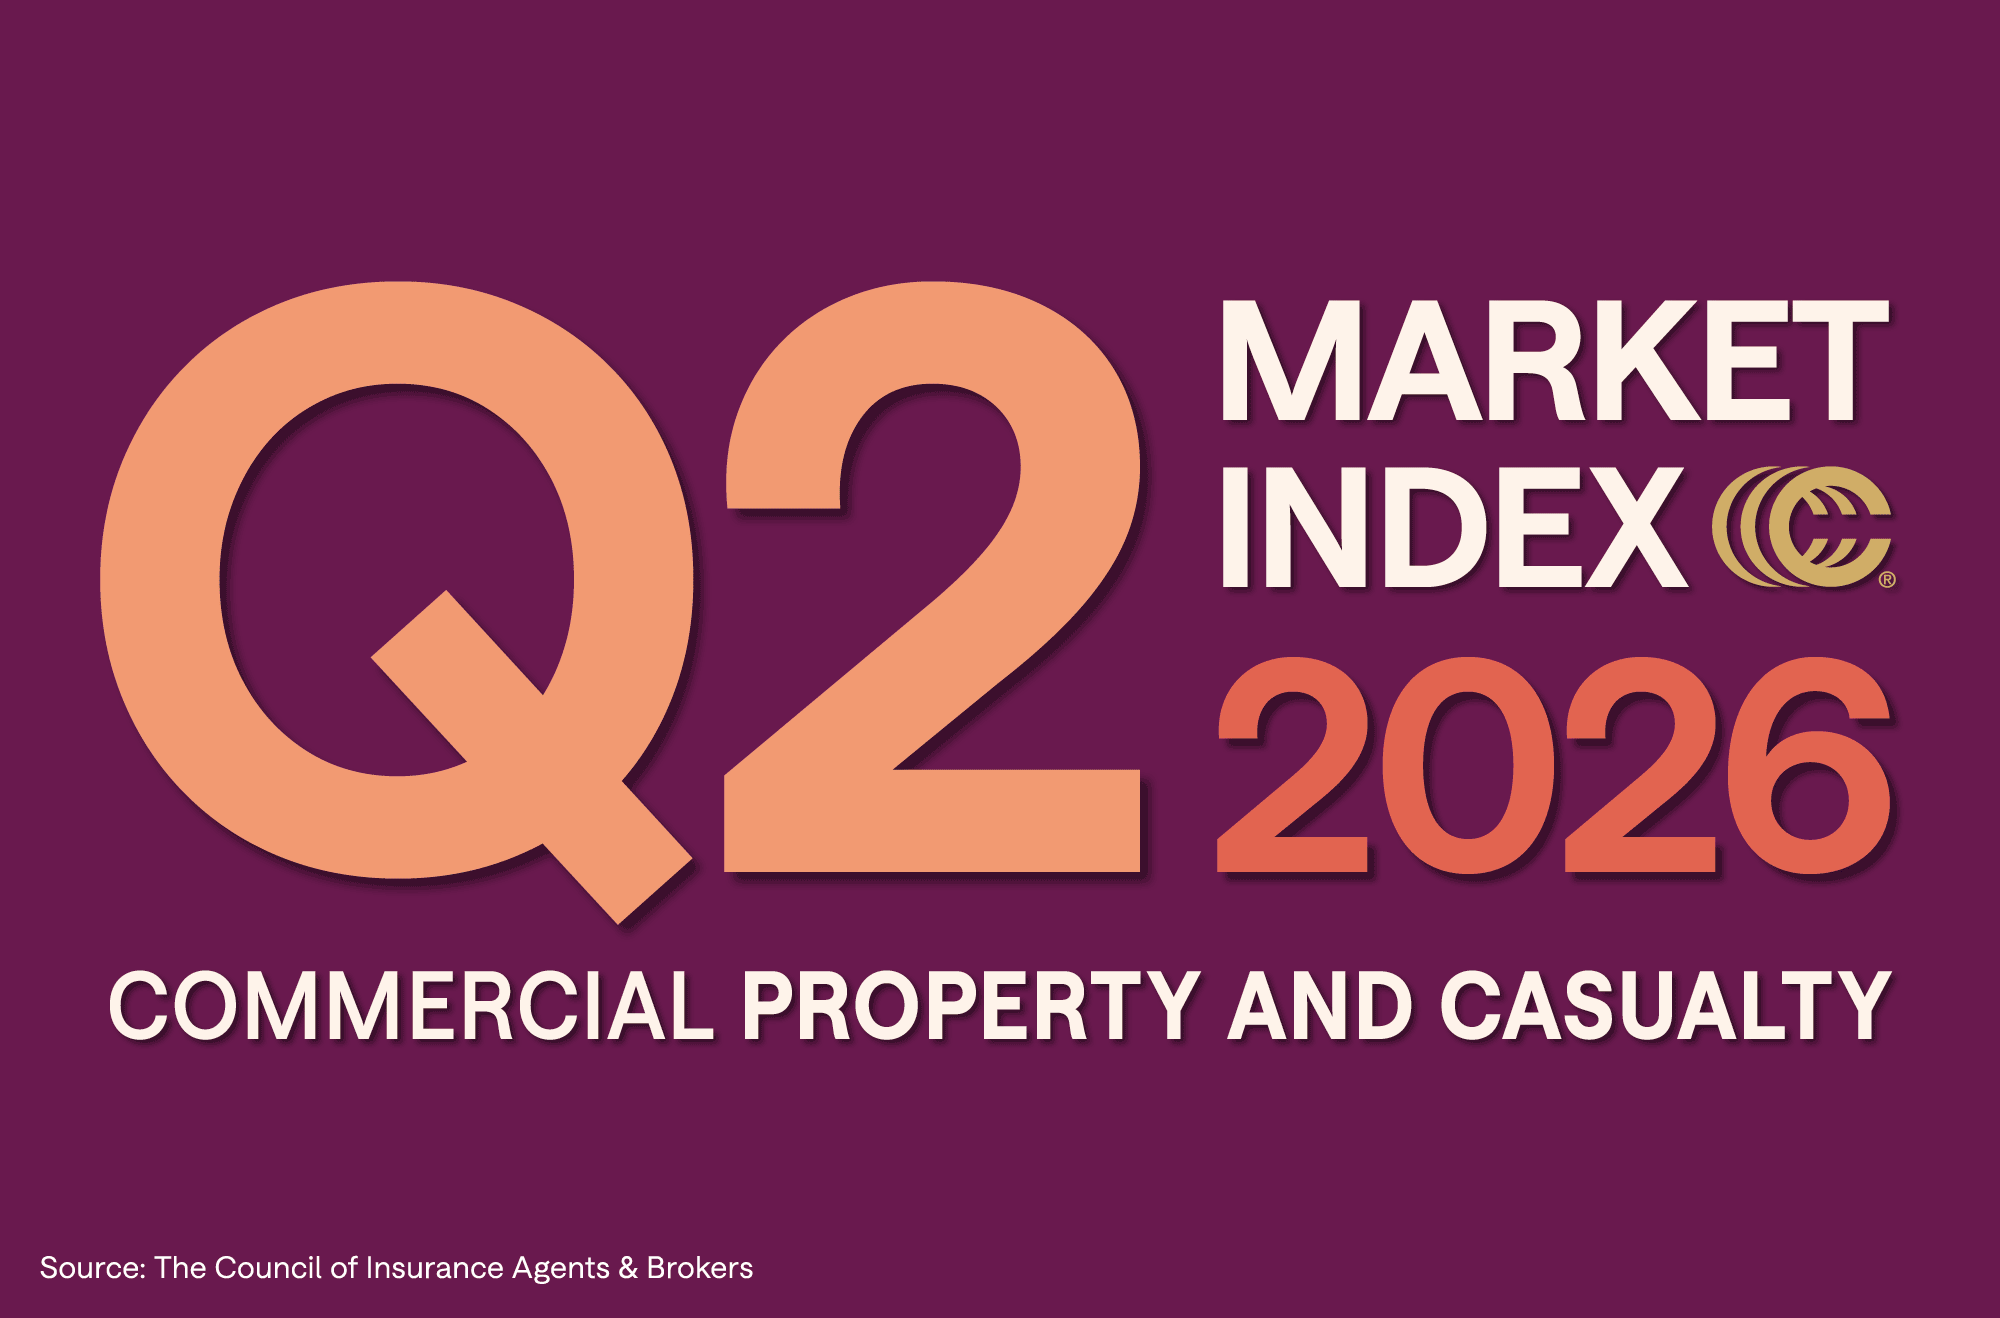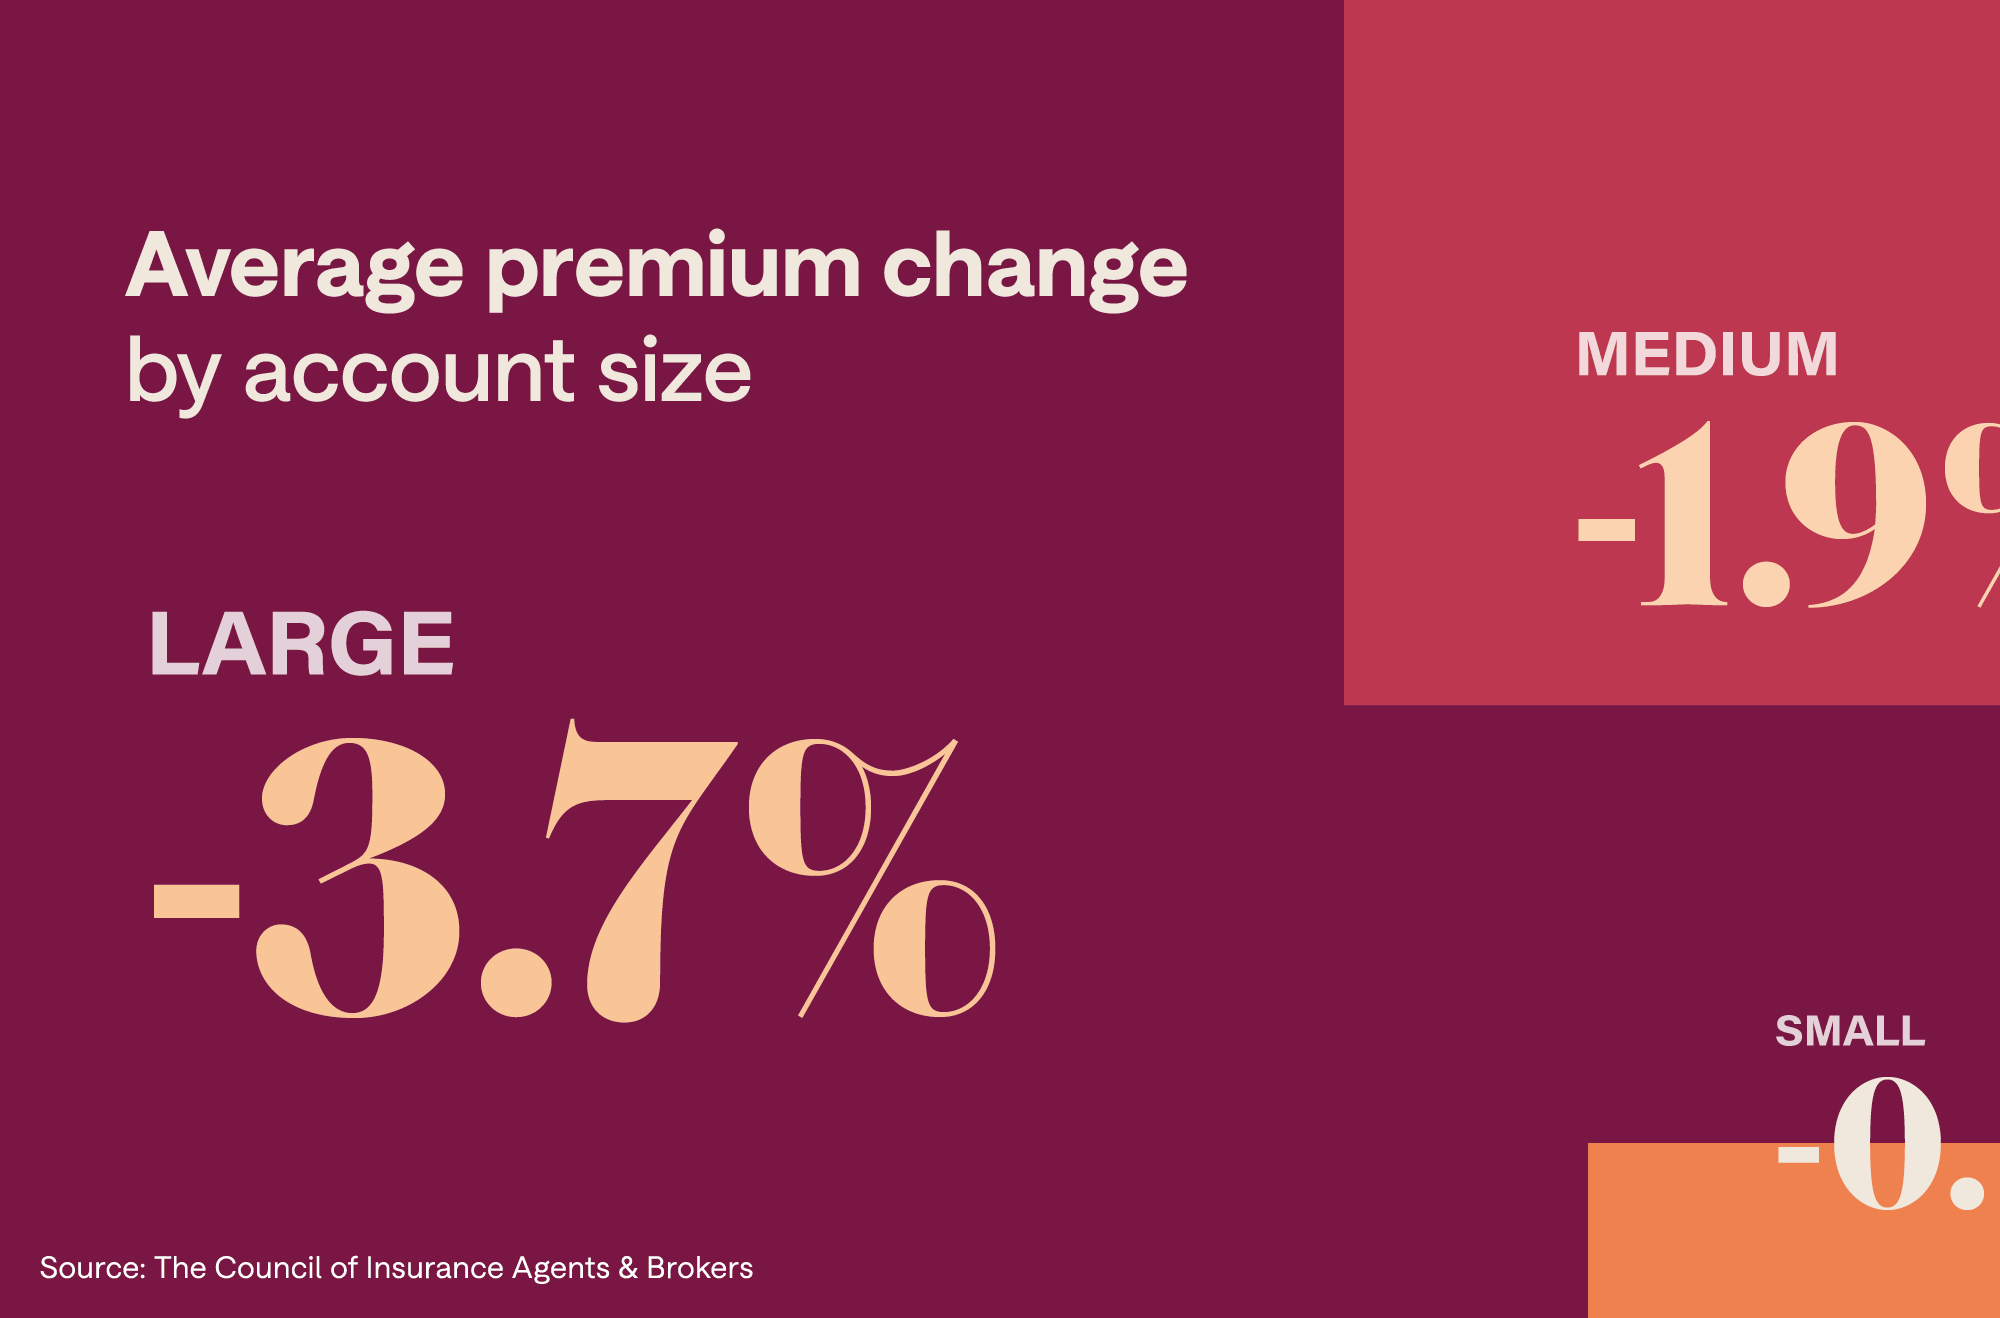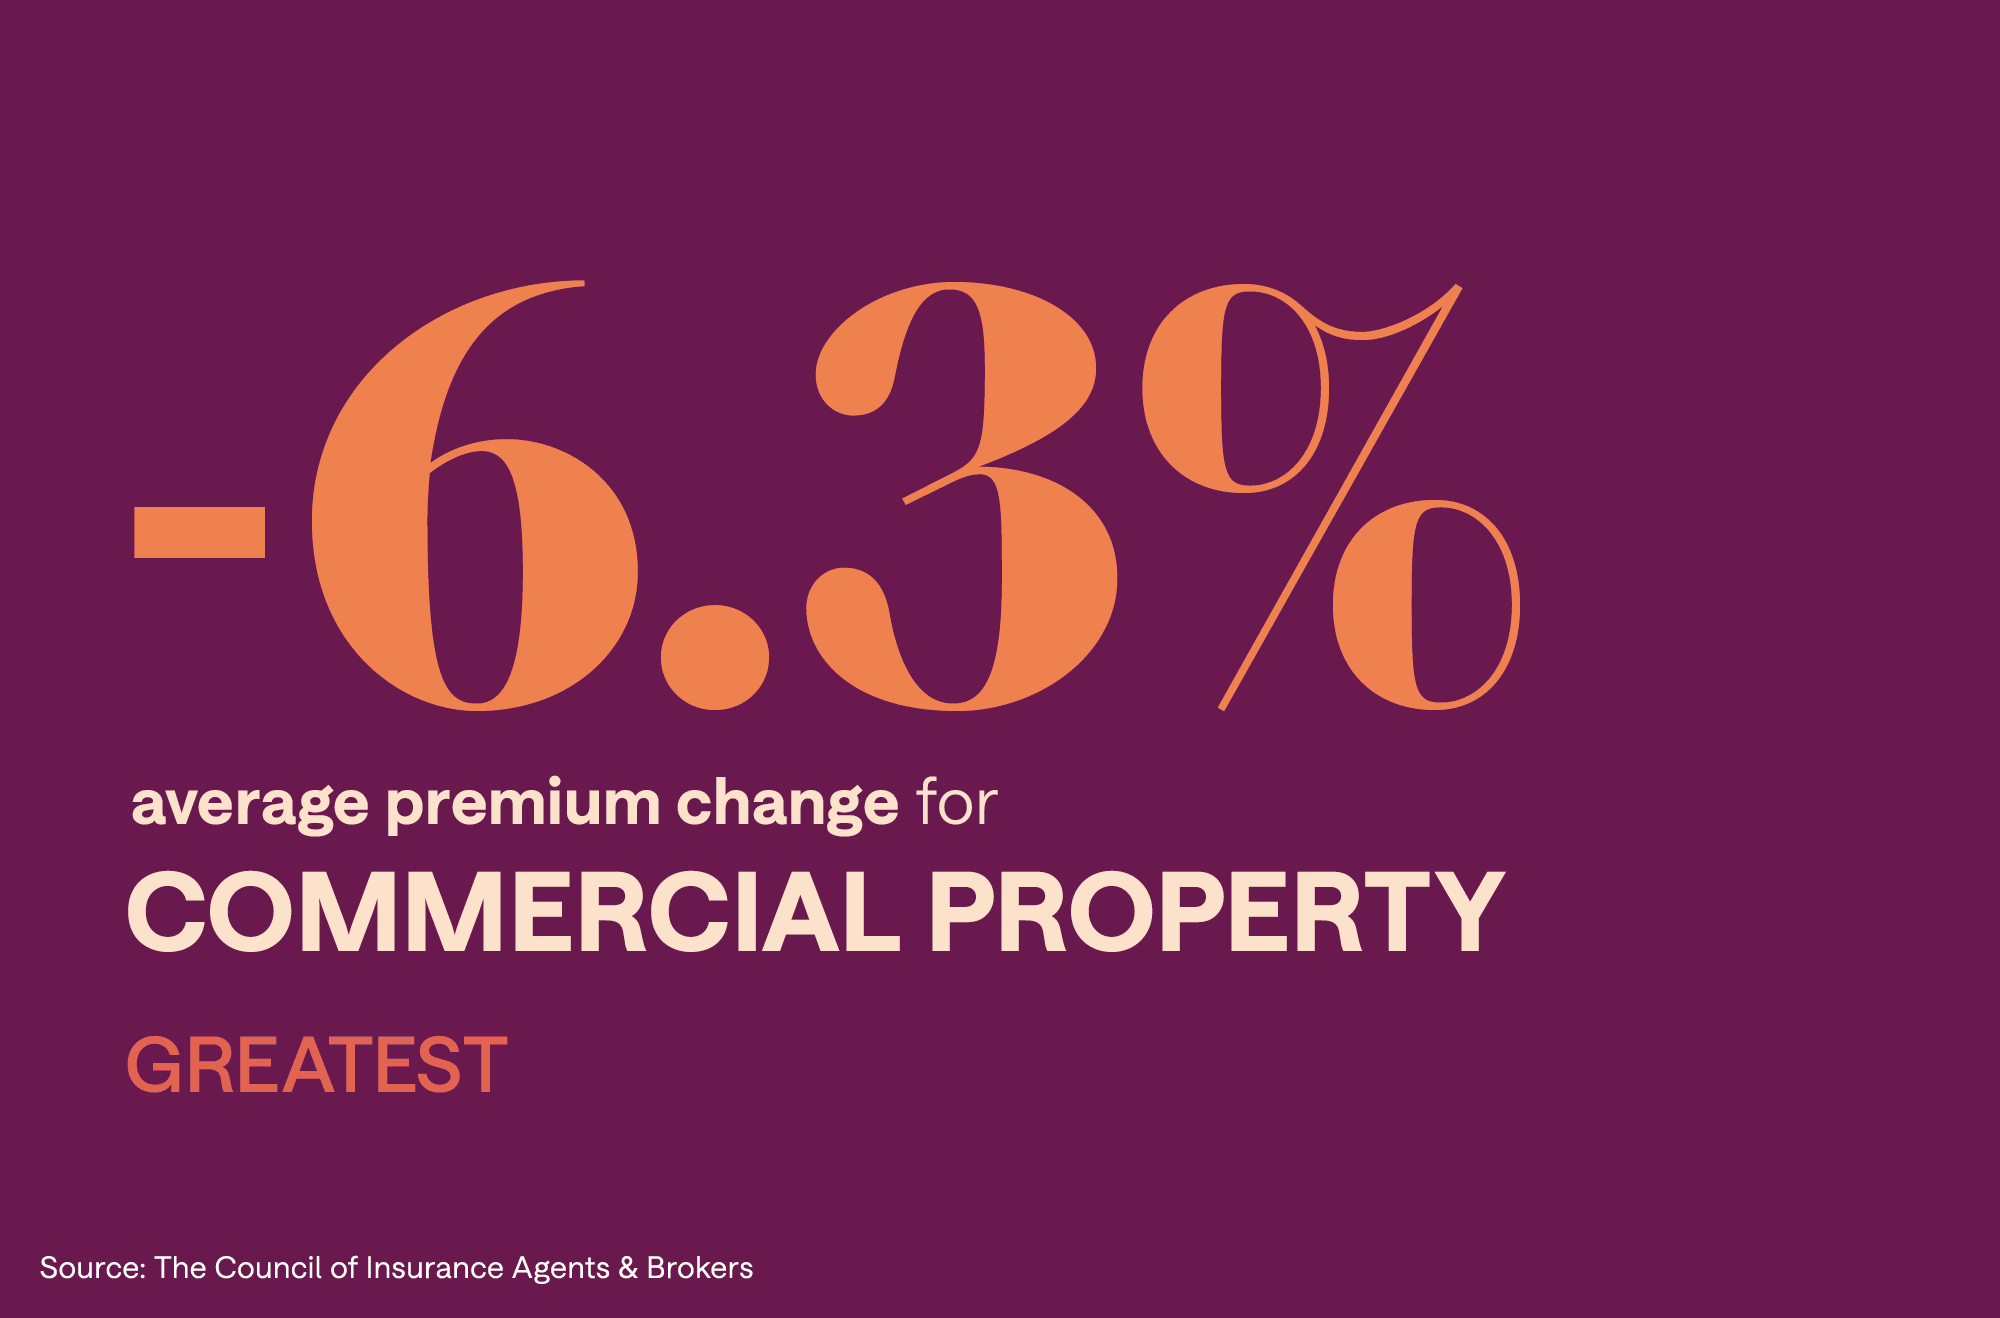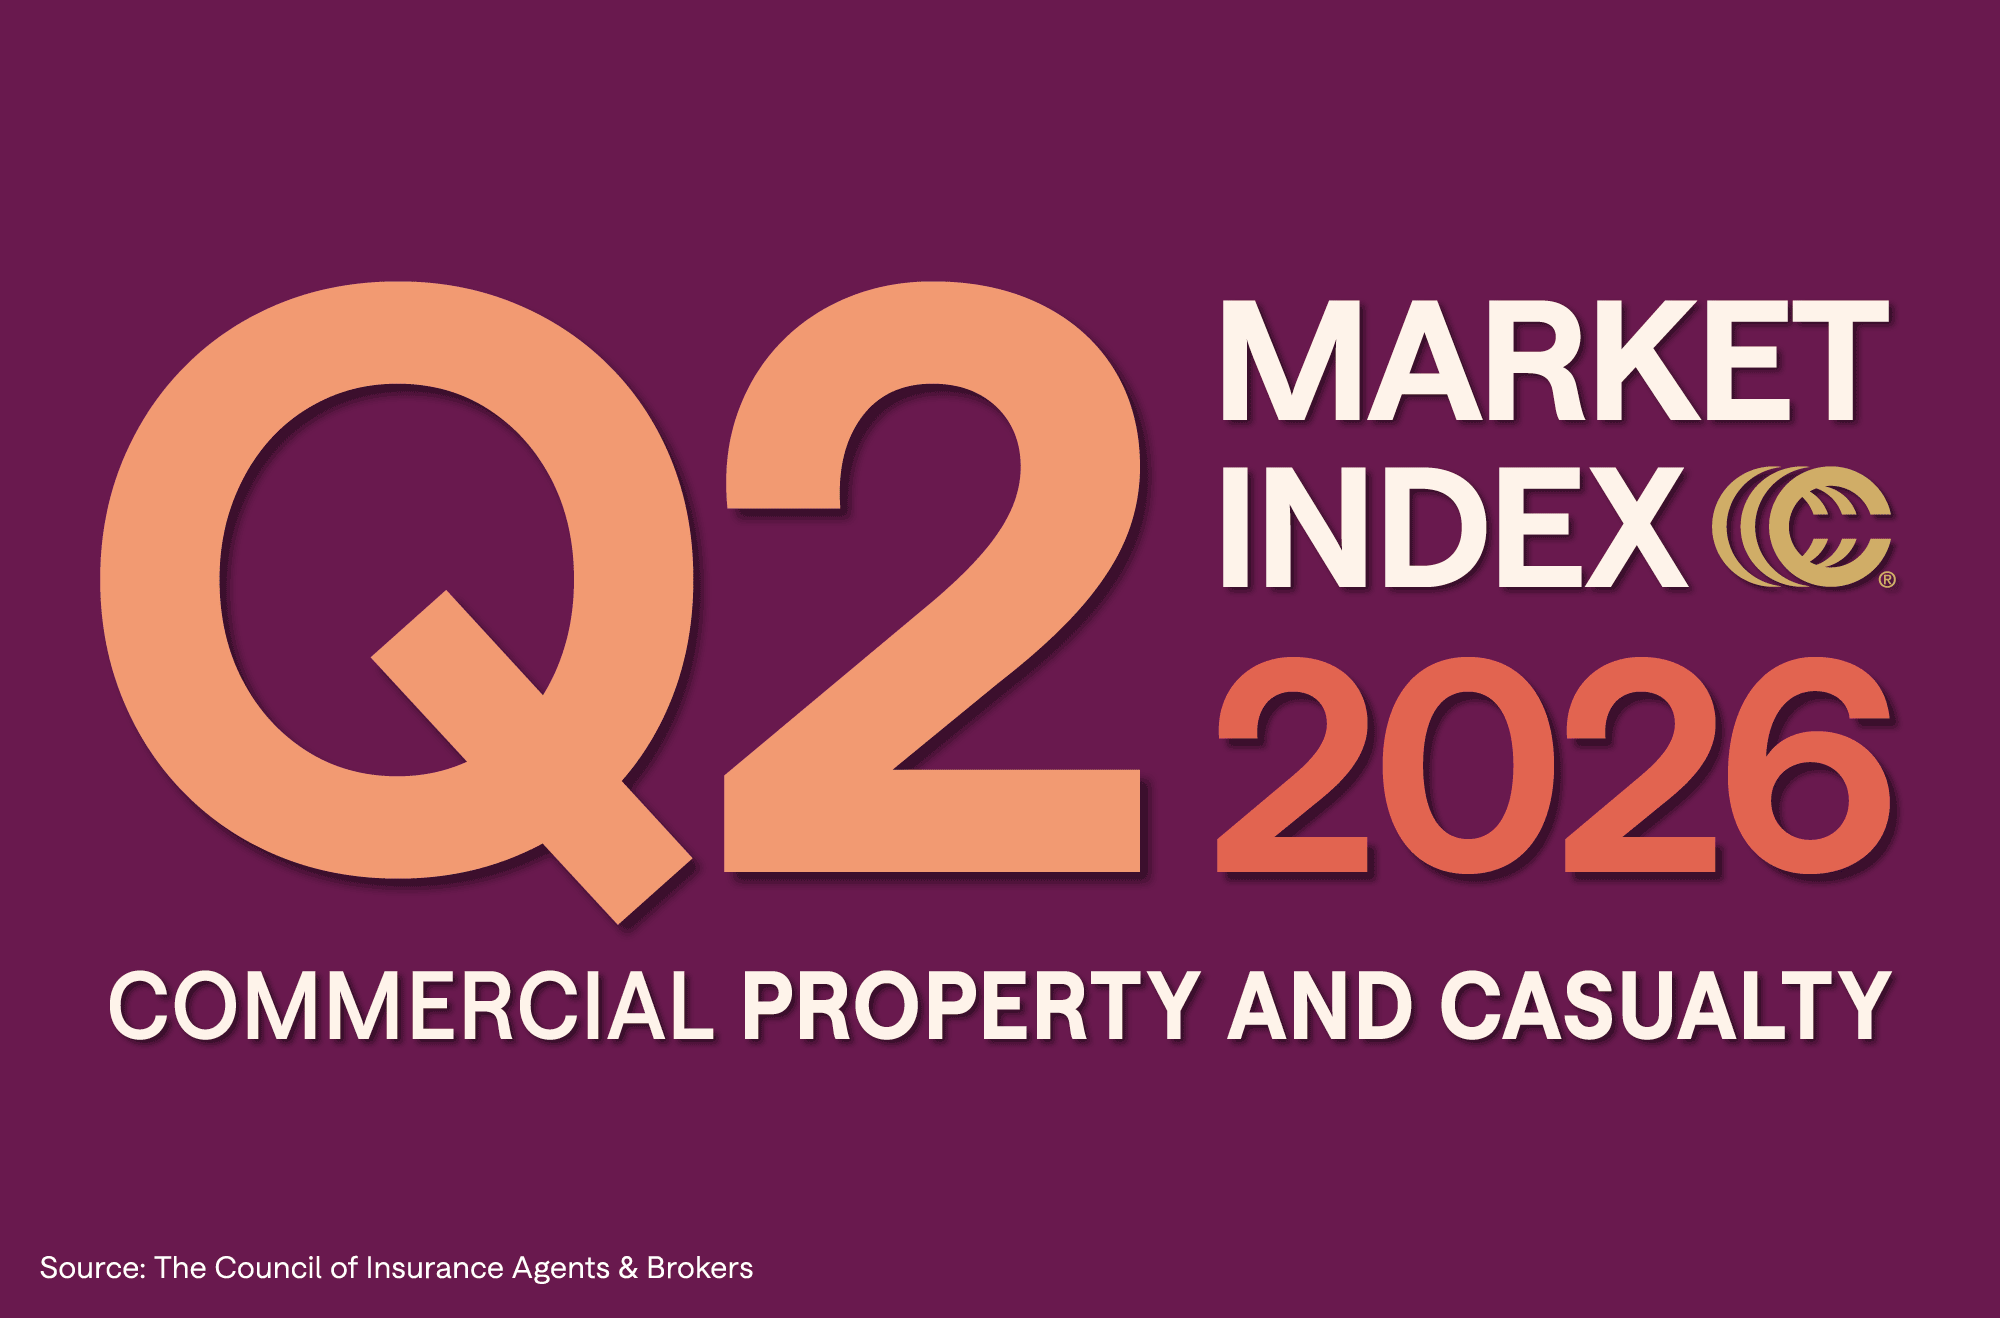
An analysis of The Council survey data by Lehman Brothers Equity Research showed that for all sizes of accounts, premiums declined an average of 9.4 percent in the first quarter. The average rate decline for small accounts was 6 percent, for medium accounts 10.9 percent, and for large accounts 11.4 percent.
The highest premiums across-the-board occurred in the fourth quarter of 2001, immediately after the terrorist attacks of Sept. 11, 2001, when the average premium increase was 28.5 percent, the Lehman analysis showed.
The Council’s Commercial Market Index showed virtually all lines of commercial P&C insurance experienced a similar downtick, with premiums stable or down by as much as 20 percent during the quarter that ended on March 31, 2005. A scattering of commercial lines such as broker errors and omissions, workers’ compensation, construction and medical malpractice experienced a slight increase in premiums of from 1-10 percent. But even those accounts more often had stable or slightly reduced rates. The Council represents the nation’s leading commercial insurance brokers who write more than 80 percent of all commercial property/casualty premiums and administer billions of dollars in employee benefits accounts annually.
In answers to open-ended questions, the brokers said the decrease in premiums was particularly noticeable in accounts representing so-called “vanilla” risks where there is little perceived exposure.
And while there still is discipline in underwriting, carriers are beginning to show more flexibility in deductibles and terms and conditions as they seek new business.
“Many average and above accounts are being targeted by competition,” said one broker from the Southwest. “Maverick carriers driving premiums down on selected accounts, searching for market share. Here we go again.”
“Carriers are more flexible in their underwriting appetite as their zeal for new business continues to influence their decisions,” said a broker from the Northeast.
Ken A. Crerar, president of The Council, said it is particularly important in times of soft market conditions for commercial customers to look to their professional insurance brokers for insight into the overall stability of carriers as well as the quality of services they provide.
“When carriers start competing for business based on who can offer the lowest premiums, issues such as solvency move to the forefront. Insurance is fundamentally based on a promise to pay, and if that promise cannot be honored, the best price may not be the best deal,” Crerar said.
The analysis of Council survey data to get the average rate increases and the attached charts based on The Council survey data were prepared by Lehman Brothers.
P&C Market Survey Contact:
Zach West
Senior Content Specialist/Copy Chief, Leader’s Edge