FOR IMMEDIATE RELEASE
Commercial P&C Pricing Continued to Stabilize in Third Quarter of 2014, According to CIAB Survey
WASHINGTON, D.C. – The commercial property and casualty market appeared to stabilize in the third quarter of 2014, with negligible price increases overall, according to The Council of Insurance Agents & Brokers’ quarterly Commercial P&C Market Index Survey.
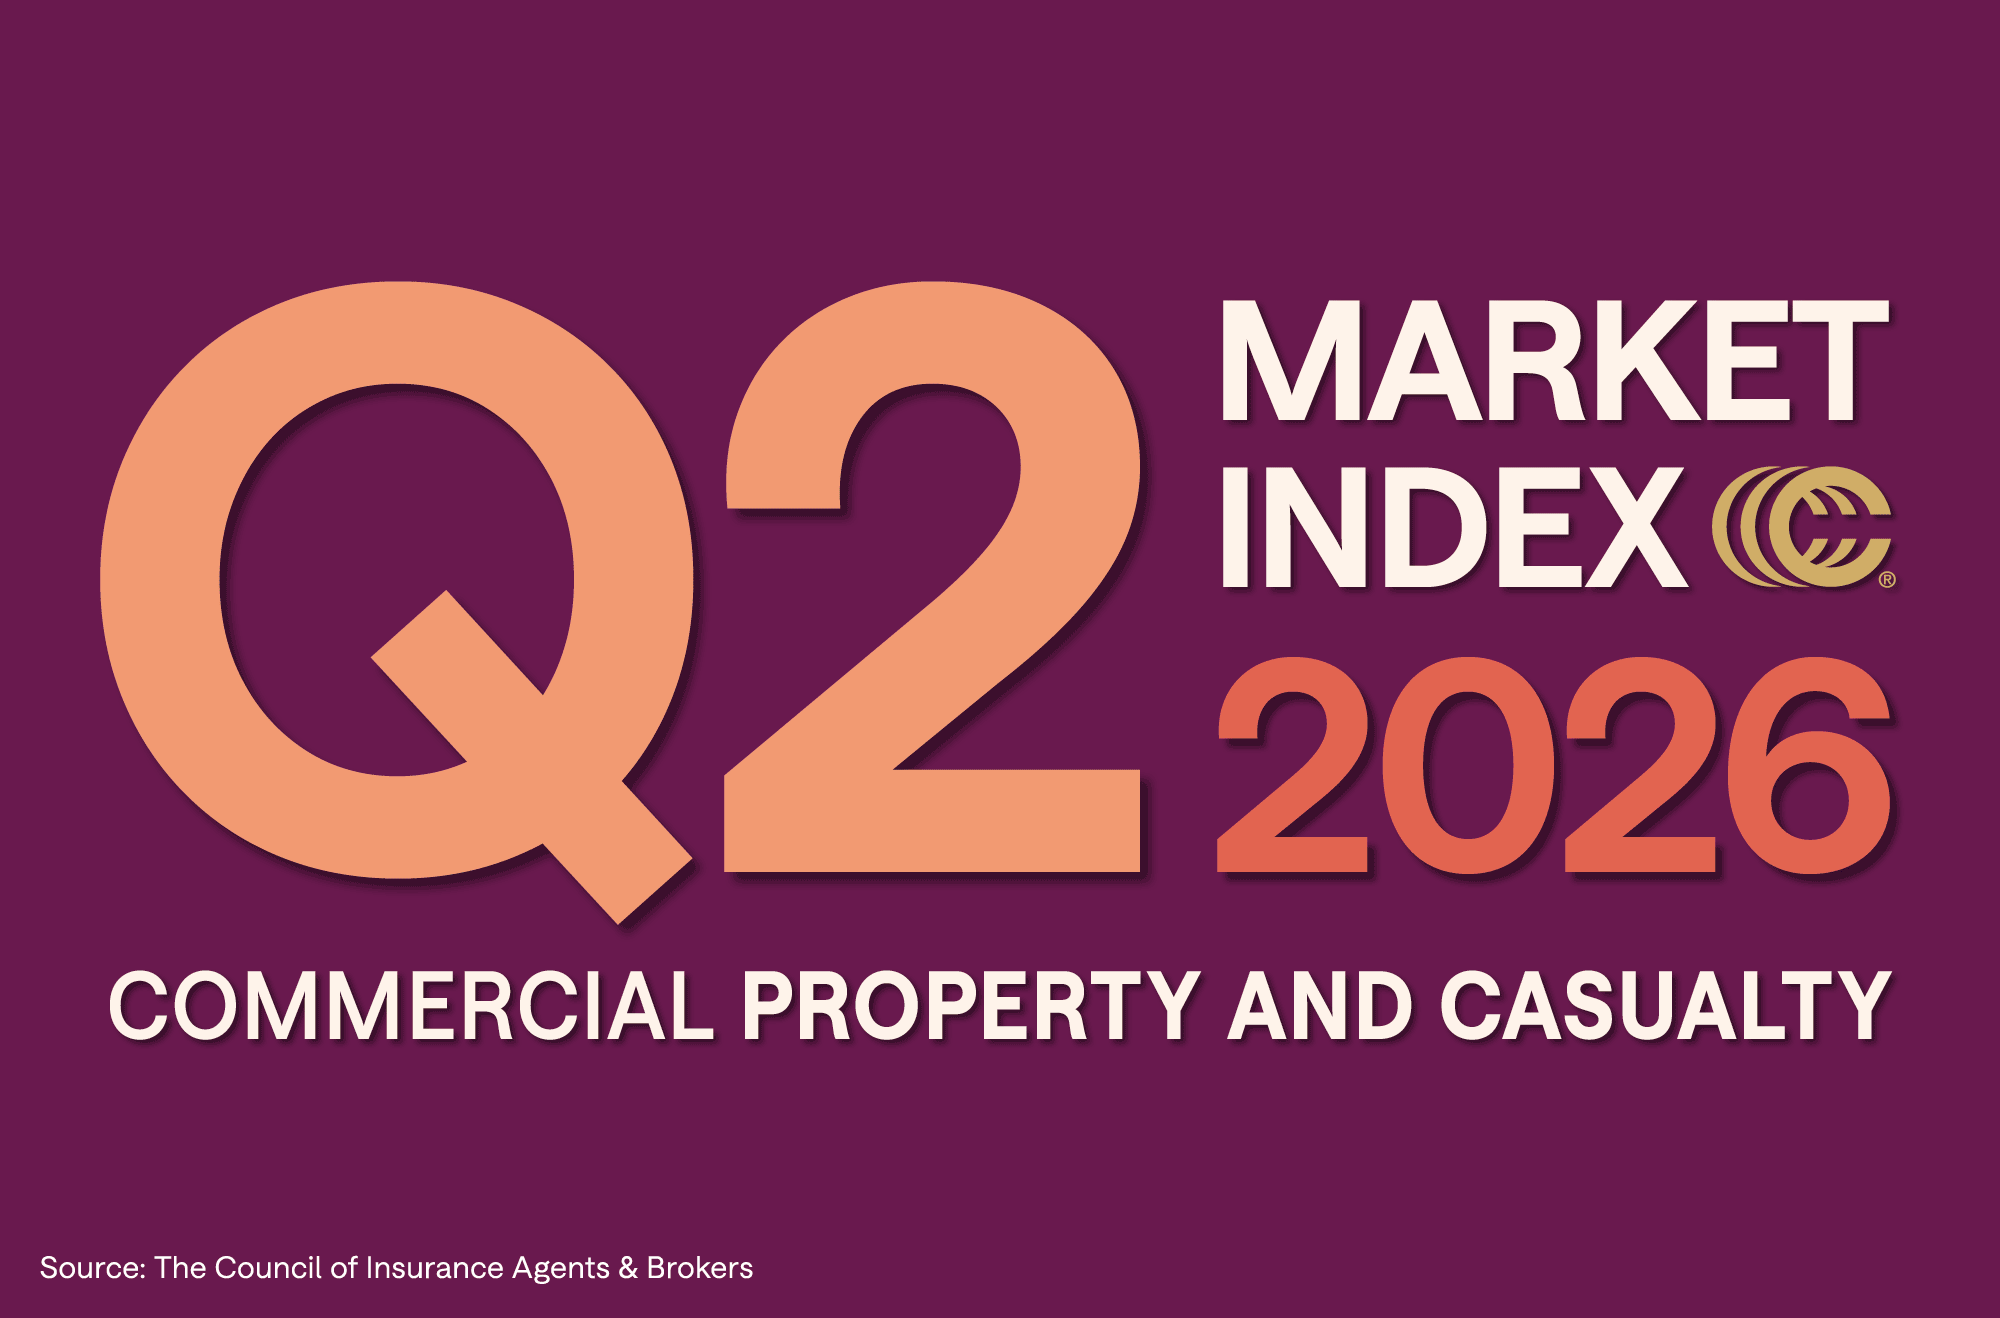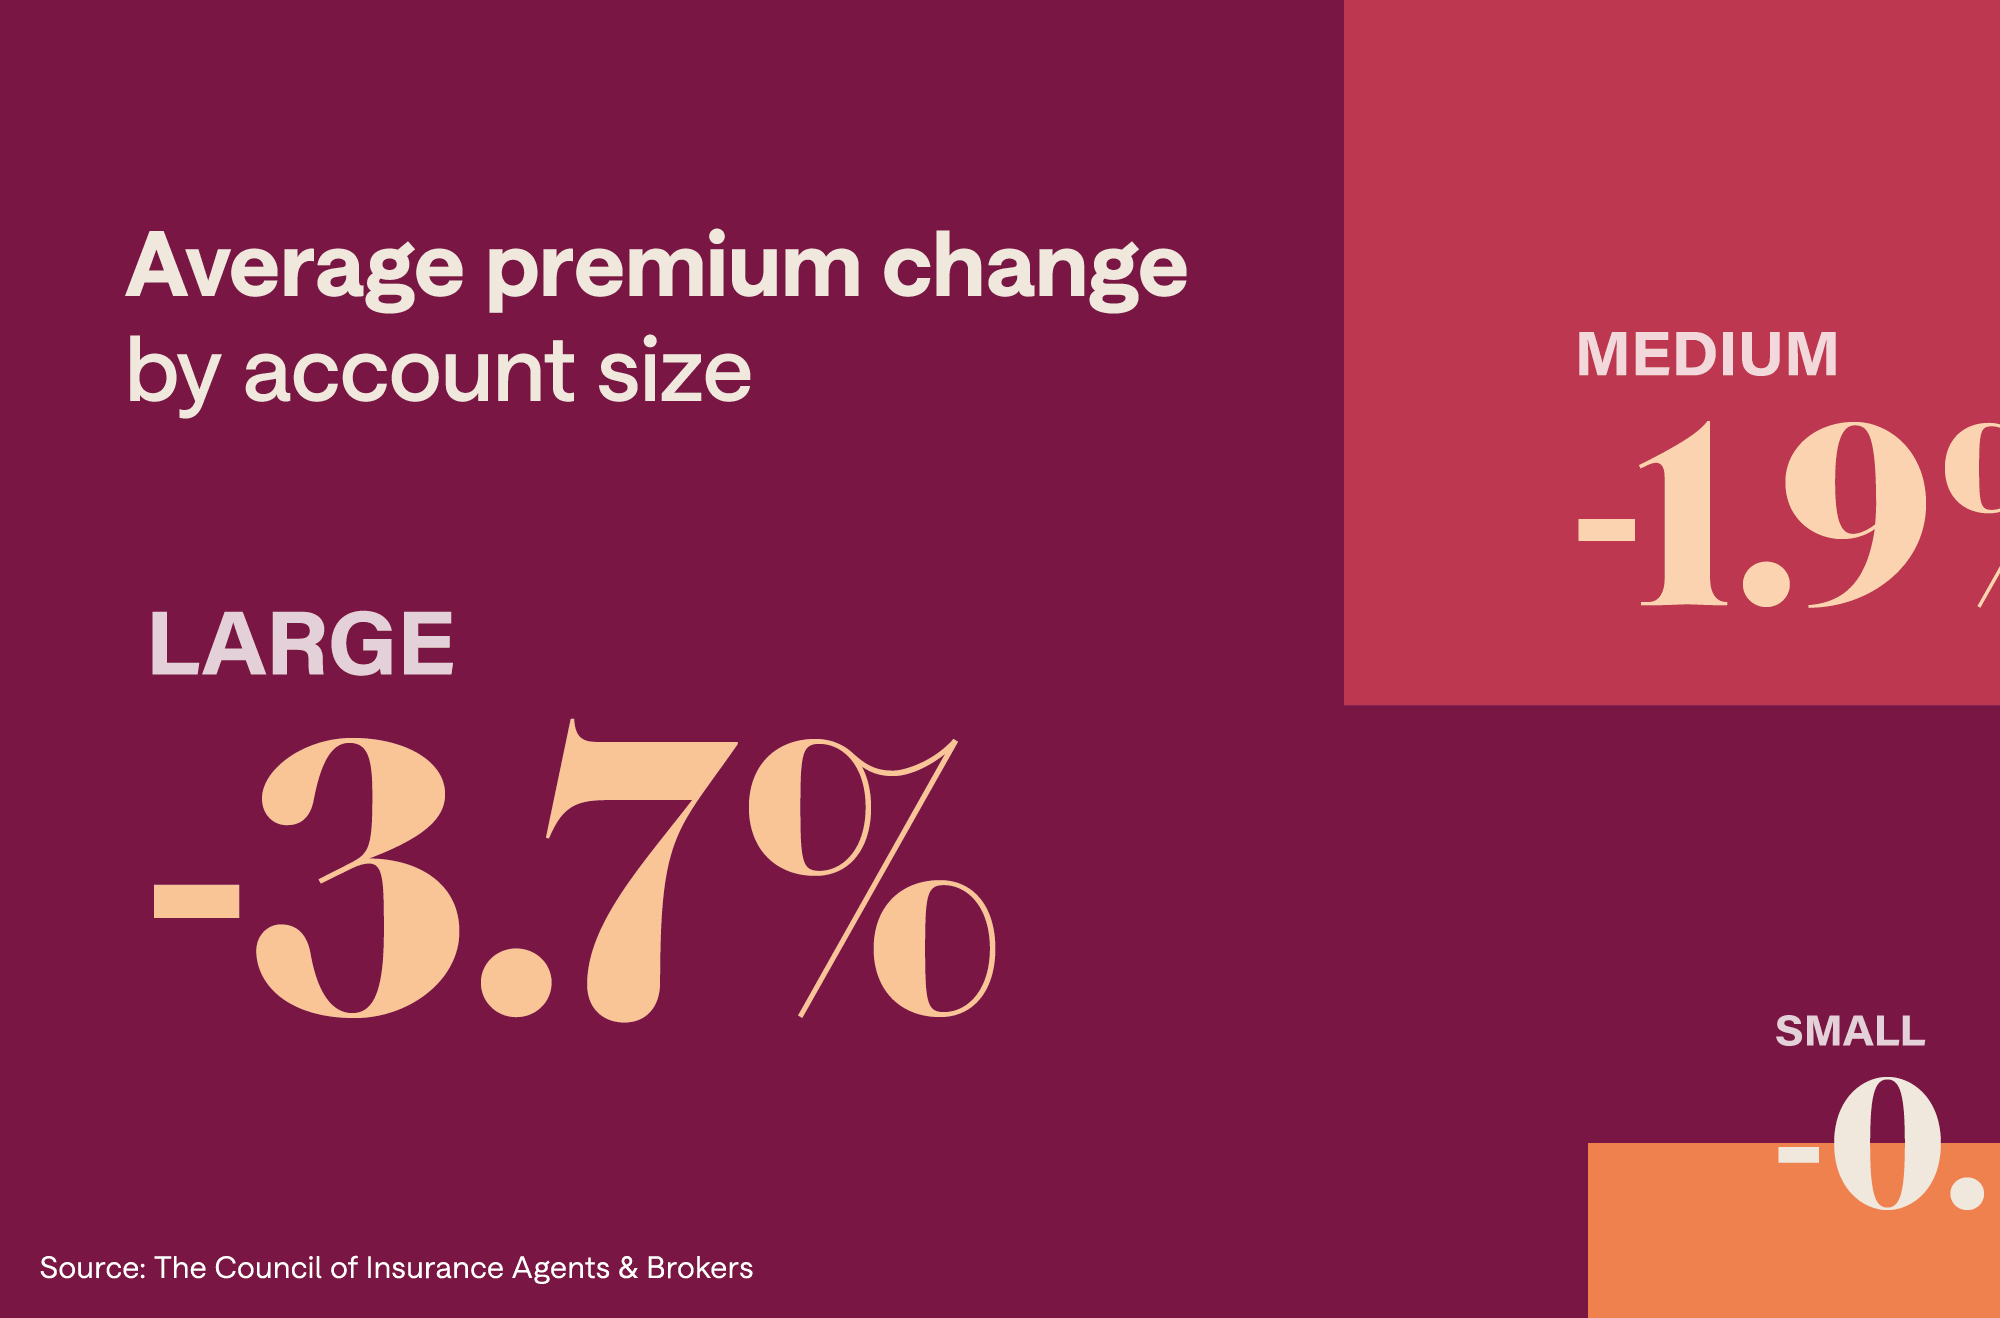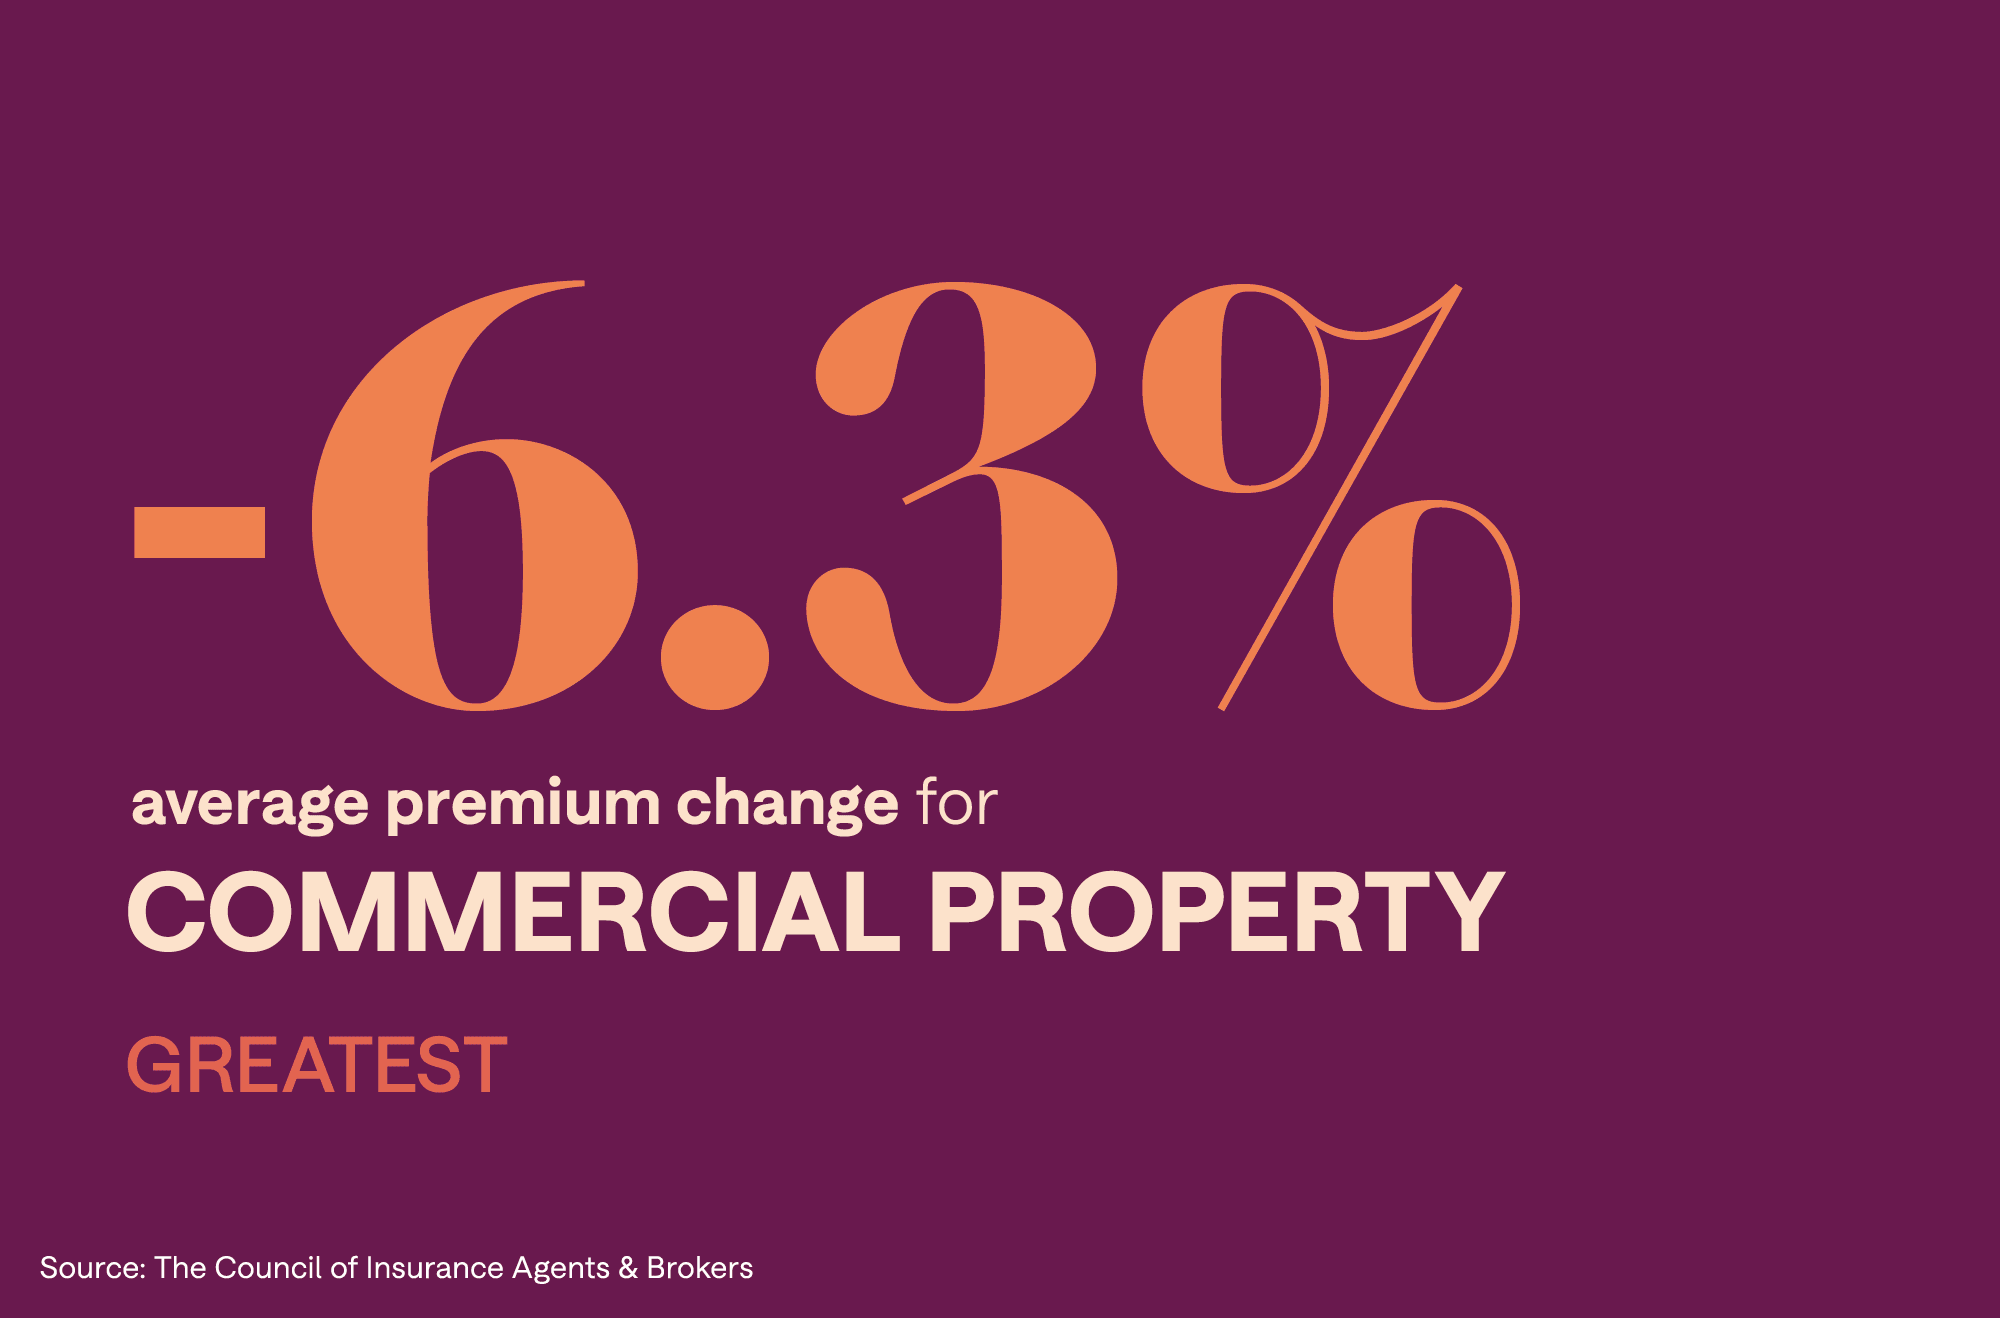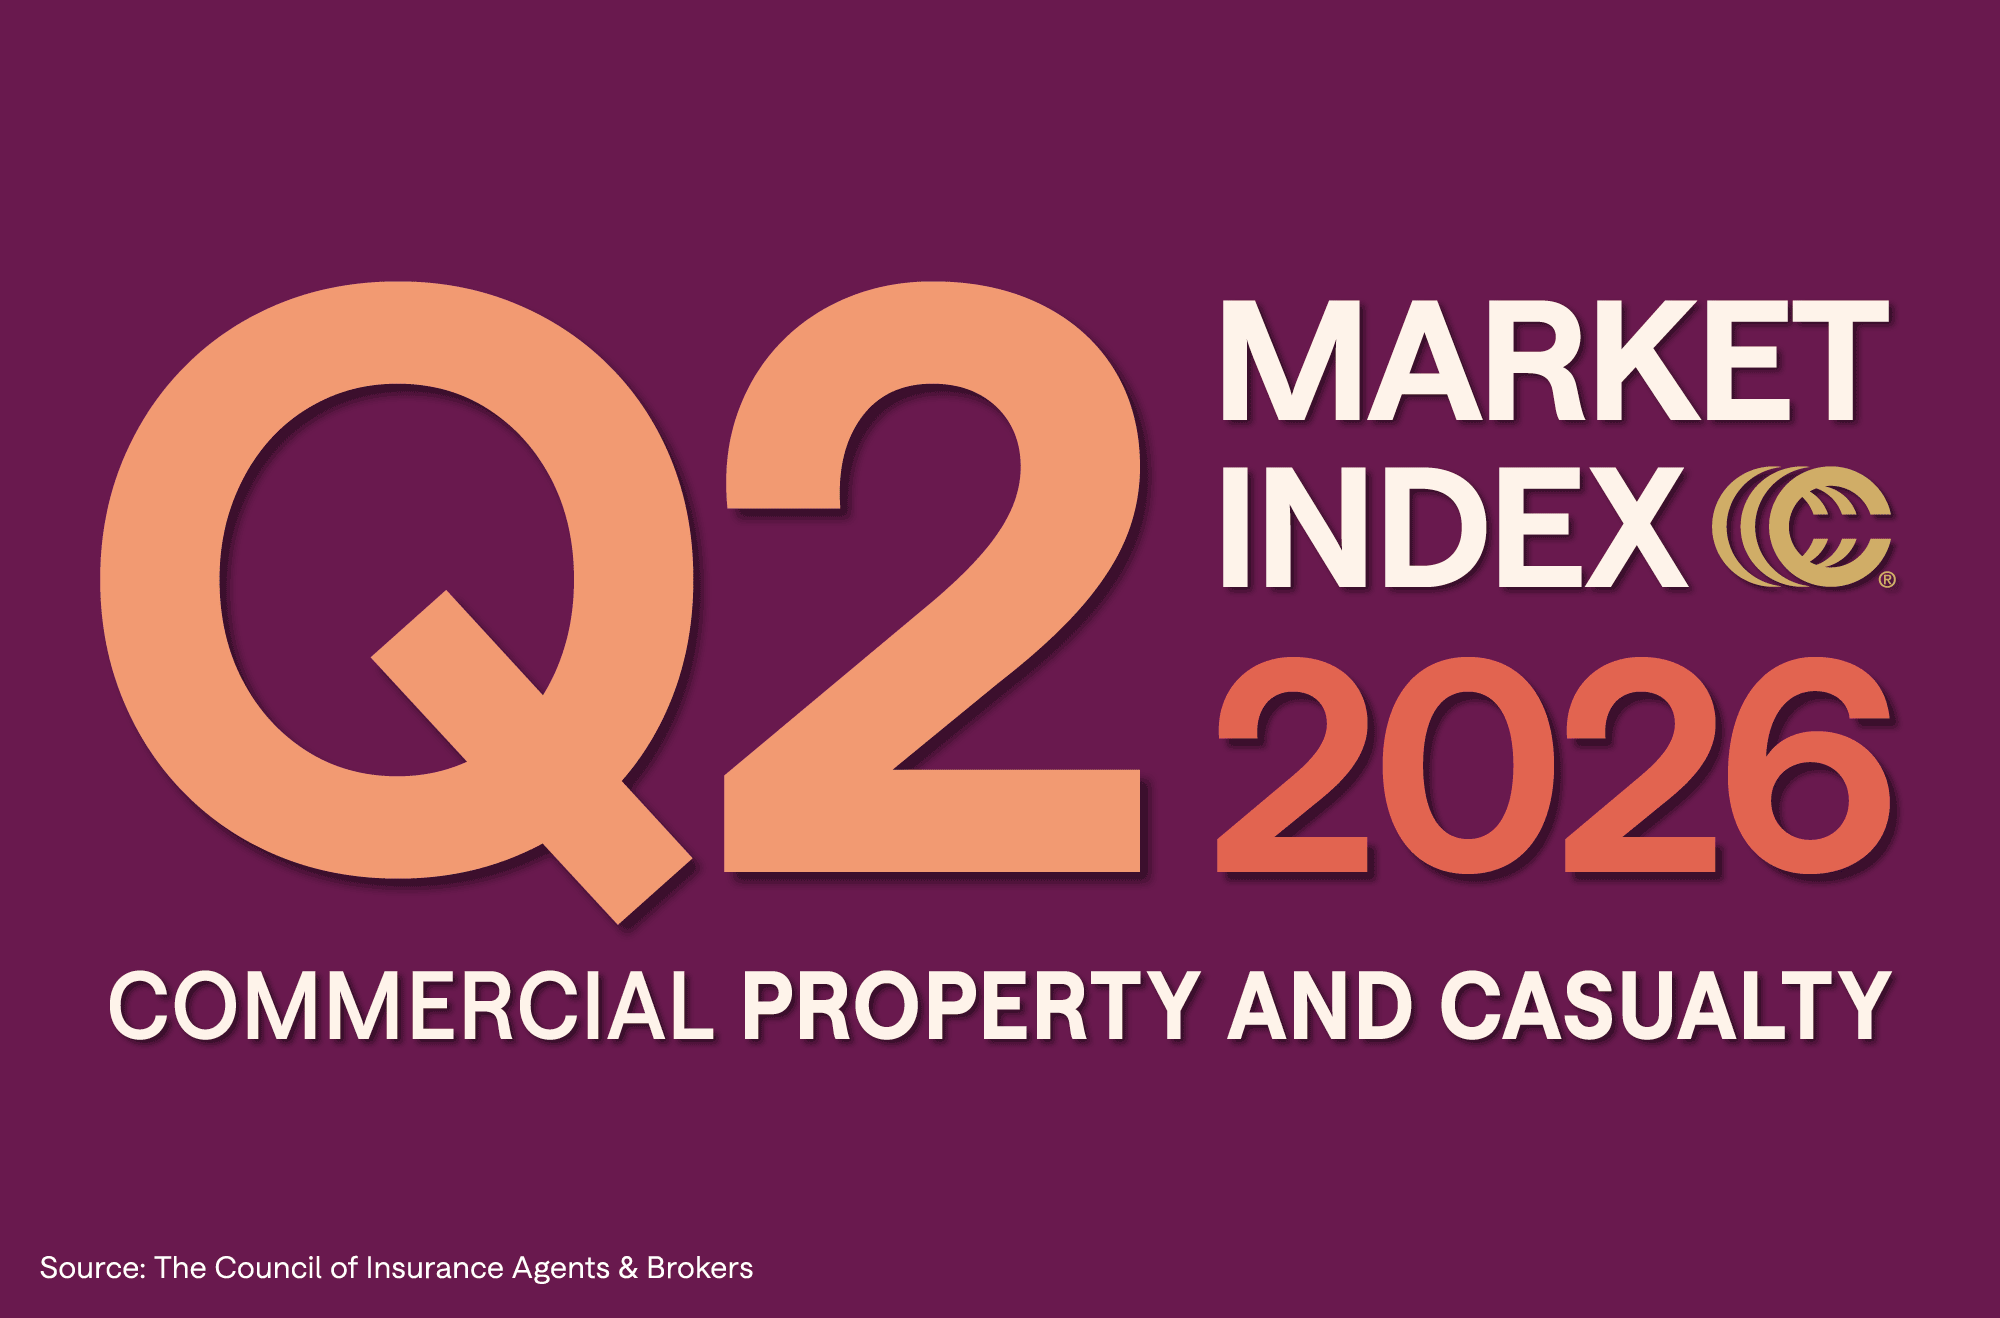
On average, small, medium and large accounts in the third quarter rose a scant 0.1 percent compared to negative 0.5 percent last quarter. Small accounts experienced the largest increase of 1.1 percent, while large accounts fell 1.1 percent as the Barclays Research chart below shows.
“We didn’t see much change in pricing or underwriters’ approach over the last quarter compared to the second quarter,” said Ken A. Crerar, president/CEO of The Council. “Capacity remained plentiful and underwriters were still eager for new business. We’ll have to wait for the fourth quarter results to see whether the third quarter portends what’s in store going forward,” Crerar said.
Many of the brokers responding to the survey said there were no significant changes in pricing or terms and conditions during the third quarter. Along the eastern seaboard, a number of brokers noted market softening for property.
The relatively calm CAT season helped keep coastal property rates stable. “Coastal wind restrictions were looser without any storms,” a broker in the Northeast reported. A Southeastern broker saw “Premium reduction in coastal/wind and an increase in competition from non-admitted markets.” Brokers in parts of the Southwest, however, struggled with wind and hail risks. As one said, “Wind/hail property deductibles are significant factors in new and renewal placements.”
The survey also found that competition dampened rate increases, due to ample capacity and a need for carriers to meet yearly underwriting goals. “More capacity means decreasing pricing and more favorable terms and conditions. The market is no longer firming,” a broker from the Southwest commented.
Capacity was bolstered additionally by specialty carriers. As one respondent observed, “Capacity in general is up in most areas due to the entrance into the marketplace of carriers like Berkshire Hathaway Specialty, which continues to set up new divisions.”
Brokers also reported that carriers continued to be aggressive on new business and were willing to negotiate on good renewal accounts to keep them from going on the market. Typical of the responses, a Northeast broker said, “Carriers continue to offer more competitive pricing and terms on clean renewal business.” A similar scenario played out in the Midwest. “Pricing is getting softer and carriers are beginning to take shots at good accounts when they get into the market.”
Topping the list of other concerns for brokers were acquiring and retaining talent, cyber and terrorism risks, competition and global challenges.
The Council’s survey is the oldest source of commercial property-casualty market conditions, pricing practices and trends, dating back to 1999.
P&C Market Survey Contact:
Zach West
Senior Content Specialist/Copy Chief, Leader’s Edge